Over the past few weeks, you’ve probably received a whole bunch of newsletters telling you about their « tracking pixel », with a button to opt out (that’s because the CNIL has just said that these pixels are just like browser cookies: you have to be told they’re being used and asked for your consent).
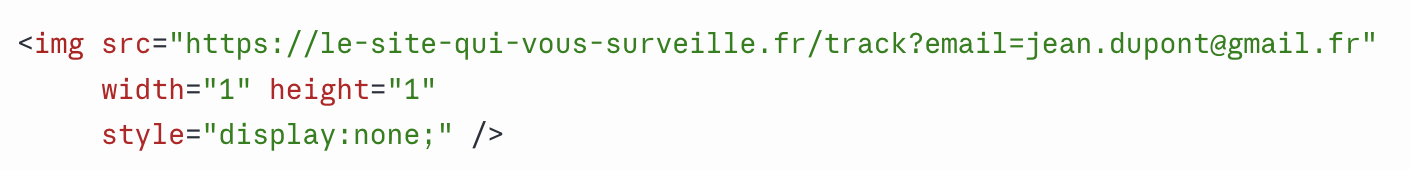
But what exactly is a tracking pixel? It’s a tiny, blank, transparent image (one pixel wide by one pixel high). Every time you open an email, this little snitch reports it back to the sender (along with the time and the device you’re on). Hence the nickname « spy pixel ».
The code behind a tracking pixel
Why do brands use them? To do all sorts of things:
If you only open emails on one topic, from then on you only get that topic (fair enough)
If you open often, you get labelled an « engaged reader » and receive even more emails (hmm, more annoying)
If you didn’t open it, the same email is sent to you again a few days later with a different subject line (not cool)
If you stop opening anything at all, the brand exports your email address to Insta, Google and YouTube to find your profile and target you with ads on those platforms (not cool at all).
At Loom, though, we do none of that: no automatic follow-ups, no segmentation based on what you open (we wouldn’t know how anyway, and we can’t be bothered to learn), no exporting your address to Instagram to show you ads (because we don’t advertise). In fact, since we refuse to push people into buying more, we don’t really need any of those features.
So we’ve switched off individual email open tracking via tracking pixel. In other words, we no longer know who opens our emails, or when. YEYEYEYE FREEDOM!
It also means we’ll no longer measure the « open rate » of our newsletters. To tell whether what we write is any good, we still have other indicators, like the unsubscribe rate… or your replies (which are always welcome): when a newsletter is rubbish, we find out very quickly ;-)
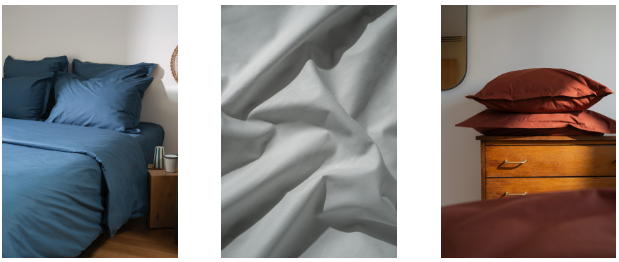
Do you know where most of the bed sheets sold in France are made? For more than half of them, the answer is Pakistan. In fact, because of competition from low-cost countries, there are hardly any bed linen factories left in France. When we found that out, we wanted to do our bit to help the last French factories hold out. Especially since we realised we could sell these sheets at prices not that far from those made on the other side of the world. How come?
Reason no. 1: bed sheets are simple products
First, the difference in manufacturing costs between sheets made in France and made in Pakistan is much smaller than it is for clothes. That’s right: while you do need quite a few machines to make sheets (looms, dyeing machines…), there’s far less sewing involved than for, say, a shirt. No need to stitch dozens of pieces of fabric together – it’s mostly hems and finishing details. In short, with household linen, the high cost of French labour is less of a handicap than it is in clothing manufacturing (if you’re interested, we’ve written a whole article about it).
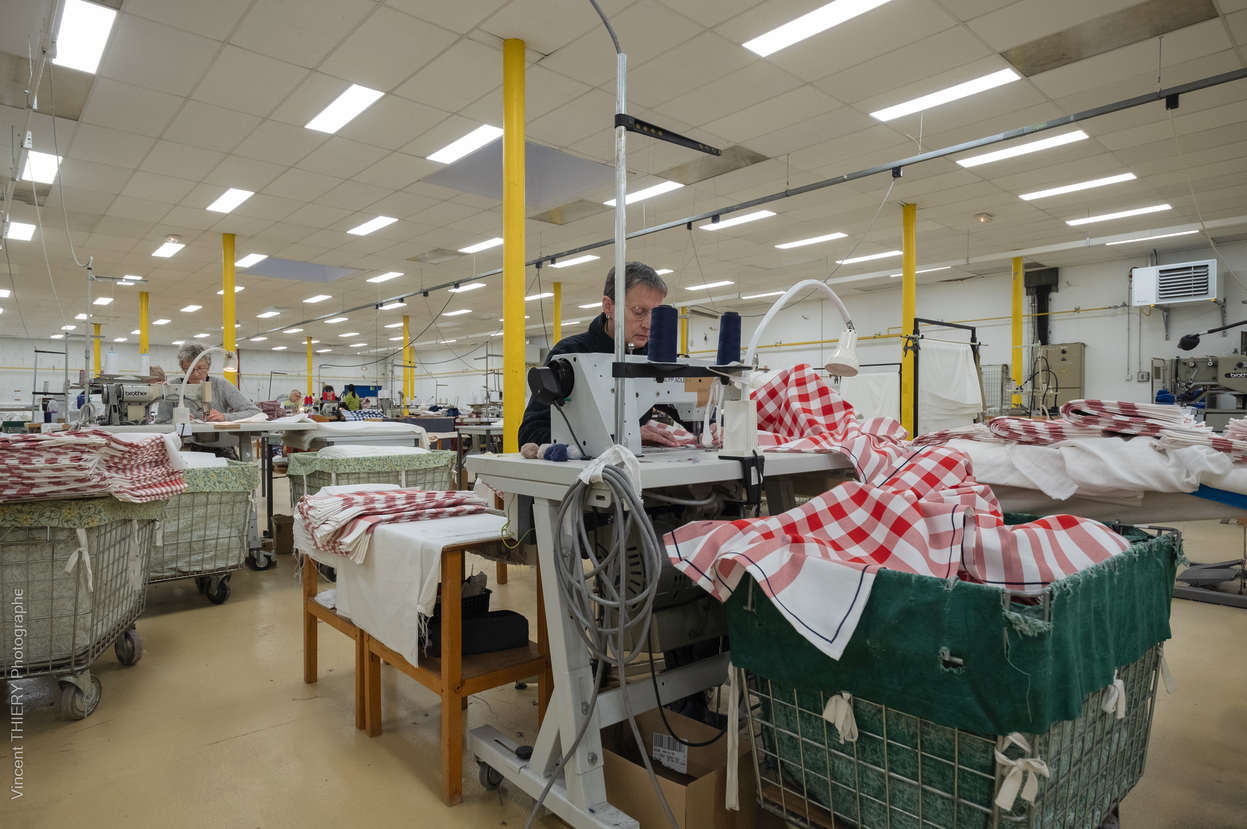
Hemming at Vogimex, our sewing factory in the Vosges, in north-eastern France (no, those aren’t our sheets in the photo)
Reason no. 2: the market is full of "over-quality"
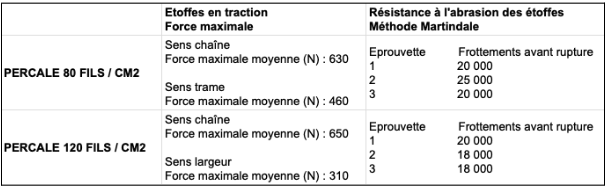
In the bed linen market, brands often put forward “120 threads per cm2” cotton percale as a sign of quality. The difference with an 80-thread percale is that the threads are finer. And the finer the threads, the more expensive the fabric.
It’s true that finer threads make the fabric softer. But while running our lab tests, we found that they also make it a little less resistant to holes and tearing.
Don’t get us wrong: cotton percale sheets are soft and top quality, whether they’re 80 or 120 threads (the threads are already very fine in both cases). But we think 80-thread percale is the better compromise: it lets us offer quality sheets that are not only more affordable and more durable, but also more breathable and less prone to creasing (the finer the threads, the more the fabric creases – and honestly, who likes ironing their sheets?).
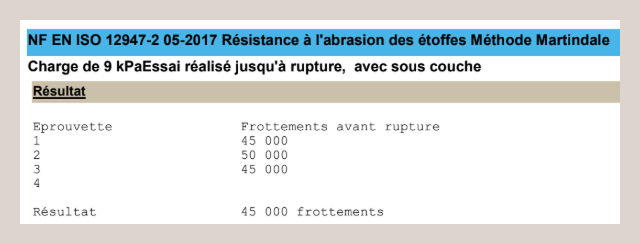
80 vs. 120-thread percale: the showdown (our lab test results)
Reason no. 3: we keep our margins low
Finally, if we can offer these sheets at affordable prices, it’s thanks to our business model: we keep our margins low because we don’t do collections (which would cost money in development and unsold stock), advertising (whose cost we’d have to pass on to the products) or sales (which would force us to charge more for the rest of the year).
In short, we can sell these made-in-France sheets at prices in line with the rest of the premium market: €80 to €90 for the duvet cover, €35 to €40 for the fitted sheet, €18 for the pillowcase. All the more so as they’re made from organic cotton (GOTS certified), whereas most sheets sold in France are made from conventional cotton (in other words, pumped full of pesticides).
We promise the choice of 3 colours wasn’t deliberate
And we’re very proud to have had them made in the Vosges, in three factories that know high-end bed linen inside out:
Tissage Mouline Thillot, a weaver that invested in modern machinery to stay competitive when many factories were moving to Asia.
Crouvezier, our dyer, who reacted very quickly when we ran into the (inevitable) production hiccups...
And then there’s Vogimex, who carefully sewed all our sheets and kept working even during January’s snowstorms in the Vosges (the worst in 10 years, apparently).
Julia and Guillaume here, the founders of Loom. We’re picking up the pen today to tell you about an injustice that’s been weighing on us. It concerns the fine-knit sweater, whose 3rd generation has just come out. We first launched this piece in 2019, in 100% merino wool. Like any wool sweater, it looks good, it’s warm, it doesn’t fade and it doesn’t stretch out. But it has one big flaw.
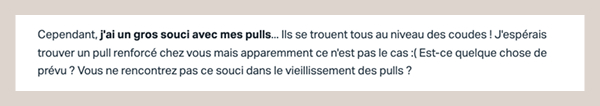
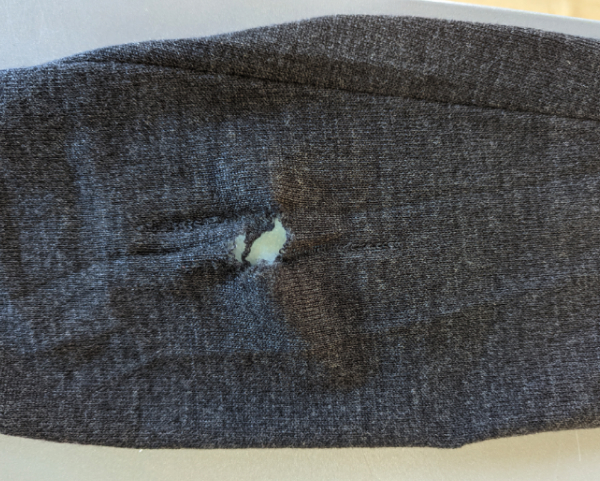
The kind of photo we used to get at customer service.
Several customers tell us that, because it’s so fine, the sweater quickly wears through at the elbows. So we stop selling it. And we look for a solution. We dive into a whirlwind of lab tests and prototype launches to confirm or rule out every one of our hypotheses.
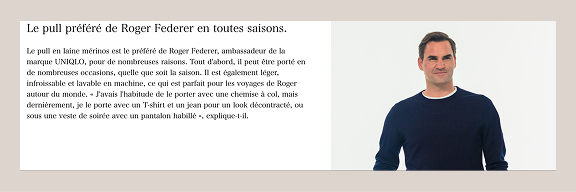
Hypothesis 1: Do other brands’ fine wool sweaters wear through as quickly as ours? Yes, even the €39.90 one from Uniqlo.
Roger clearly doesn’t lean his elbows on a desk very often.
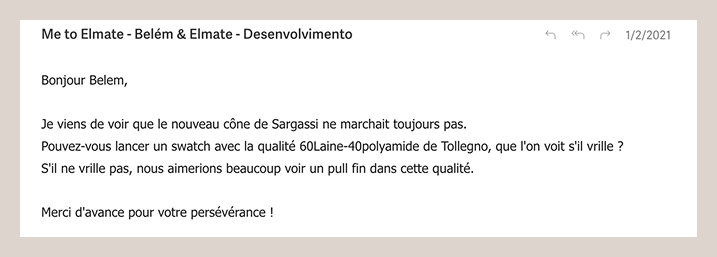
Hypothesis 2 : Does adding a bit of synthetic fibre work? No.
Email sent to the factory that knits our sweaters, asking them to add polyamide to the sweater. Spoiler: it came out all twisted.
Hypothesis 3 : Can we knit it with synthetic fibre added only at the elbows? Yes, but then the sweater becomes ridiculously expensive…
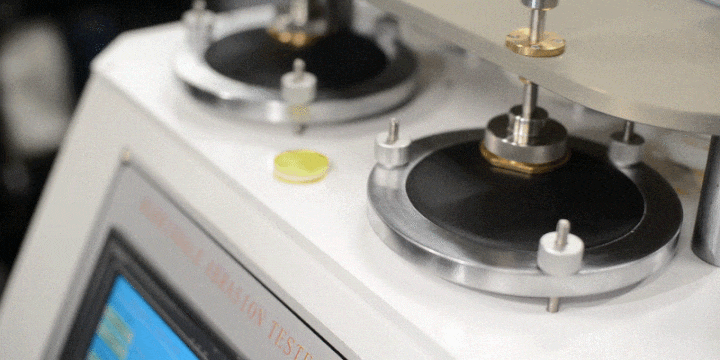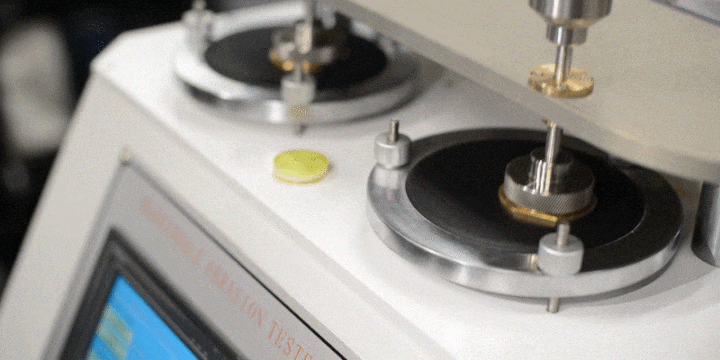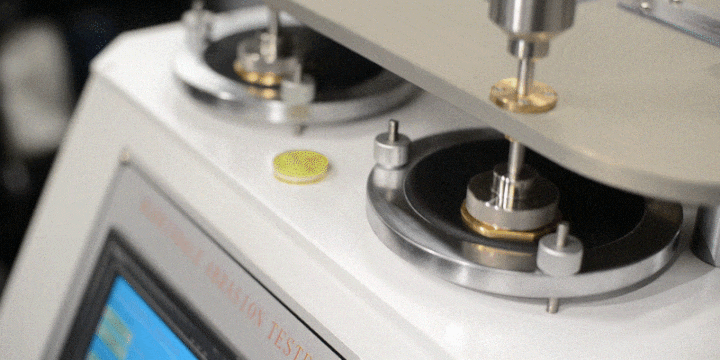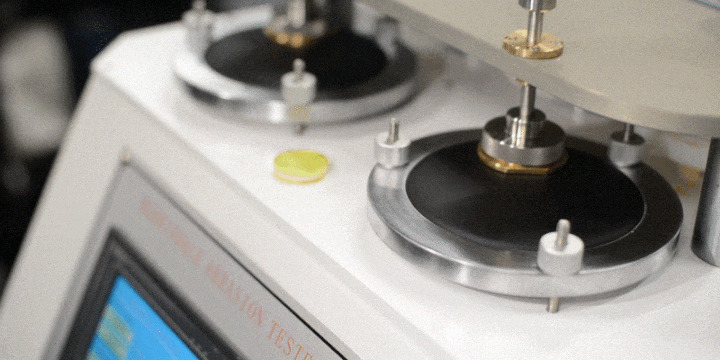
After a few months, we have to face facts: we need to launch this fine-knit sweater… in 100% cotton. Because when it comes to abrasion, it’s no contest: cotton is far more resistant than wool.
When we test it in the lab, our cotton fine-knit sweater prototype withstands 80,000 cycles, compared with 14,000 for its wool equivalent.
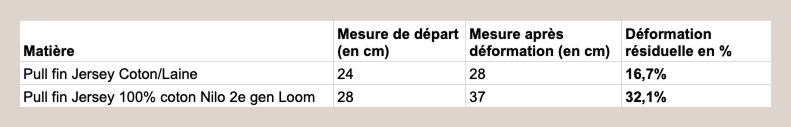
So in 2020, we release the 2nd generation of our fine-knit sweater, in Egyptian organic cotton with deep colours. This time, no more holes at the elbows… but we’ve lost the benefits of wool: odour resistance, warmth and shape retention. Don’t get us wrong: this sweater is really not bad (our customers give it an average rating of 4.8/5), but we just can’t bring ourselves to be satisfied with it. So, here too, we decide to stop selling it. We tell ourselves we’ll never manage to make a fine-knit sweater that’s both warm and durable, and we drop the project. Until one day in February 2024, when a factory tells us about a 53% wool, 47% cotton blend yarn. And then, LIGHTBULB MOMENT: could this be the answer to a fine-knit sweater that’s warm, good-looking, and resistant to losing its shape AND to abrasion? Without a second thought, we develop a prototype and test it in the lab. The results:
This fine-knit sweater is 3 times more resistant at the elbows than a 100% wool one (which, as a reminder, only lasted 14,000 cycles).
This fine-knit sweater is 2 times more resistant to losing its shape than a 100% cotton one.
Champagne! We hug, we cry, we start a conga line: at last, we’ve found the revolutionary process for making a fine-knit sweater that holds up. We can finally launch our 3rd-generation fine-knit sweater. Except that when we tell the rest of the team about this INCREDIBLE innovation, we get awkward silences at best, and more often than not, barely concealed mockery: “wow, you’ve made a sweater in a wool-cotton blend…”
Luckily, it’s all water off a duck’s back. We won’t be inviting them to the ceremony when we win first prize at the Concours Lépine, France’s famous inventors’ competition.
Julia & Guillaume
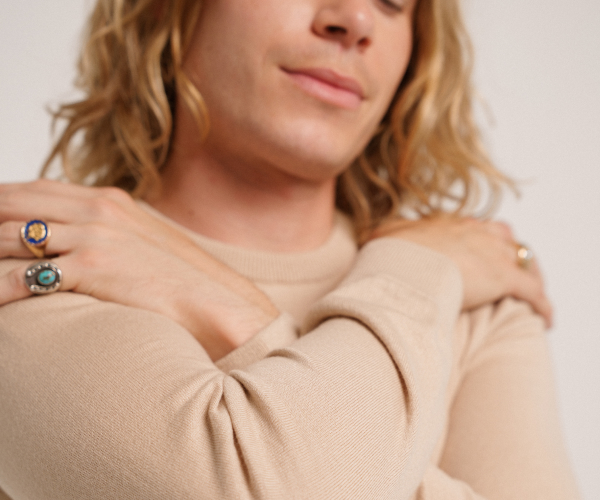
The 3rd-generation fine-knit sweater – good-looking too, isn’t it?
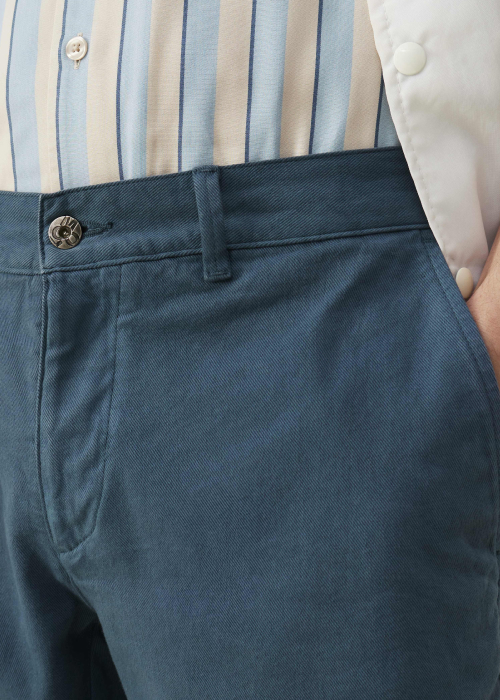
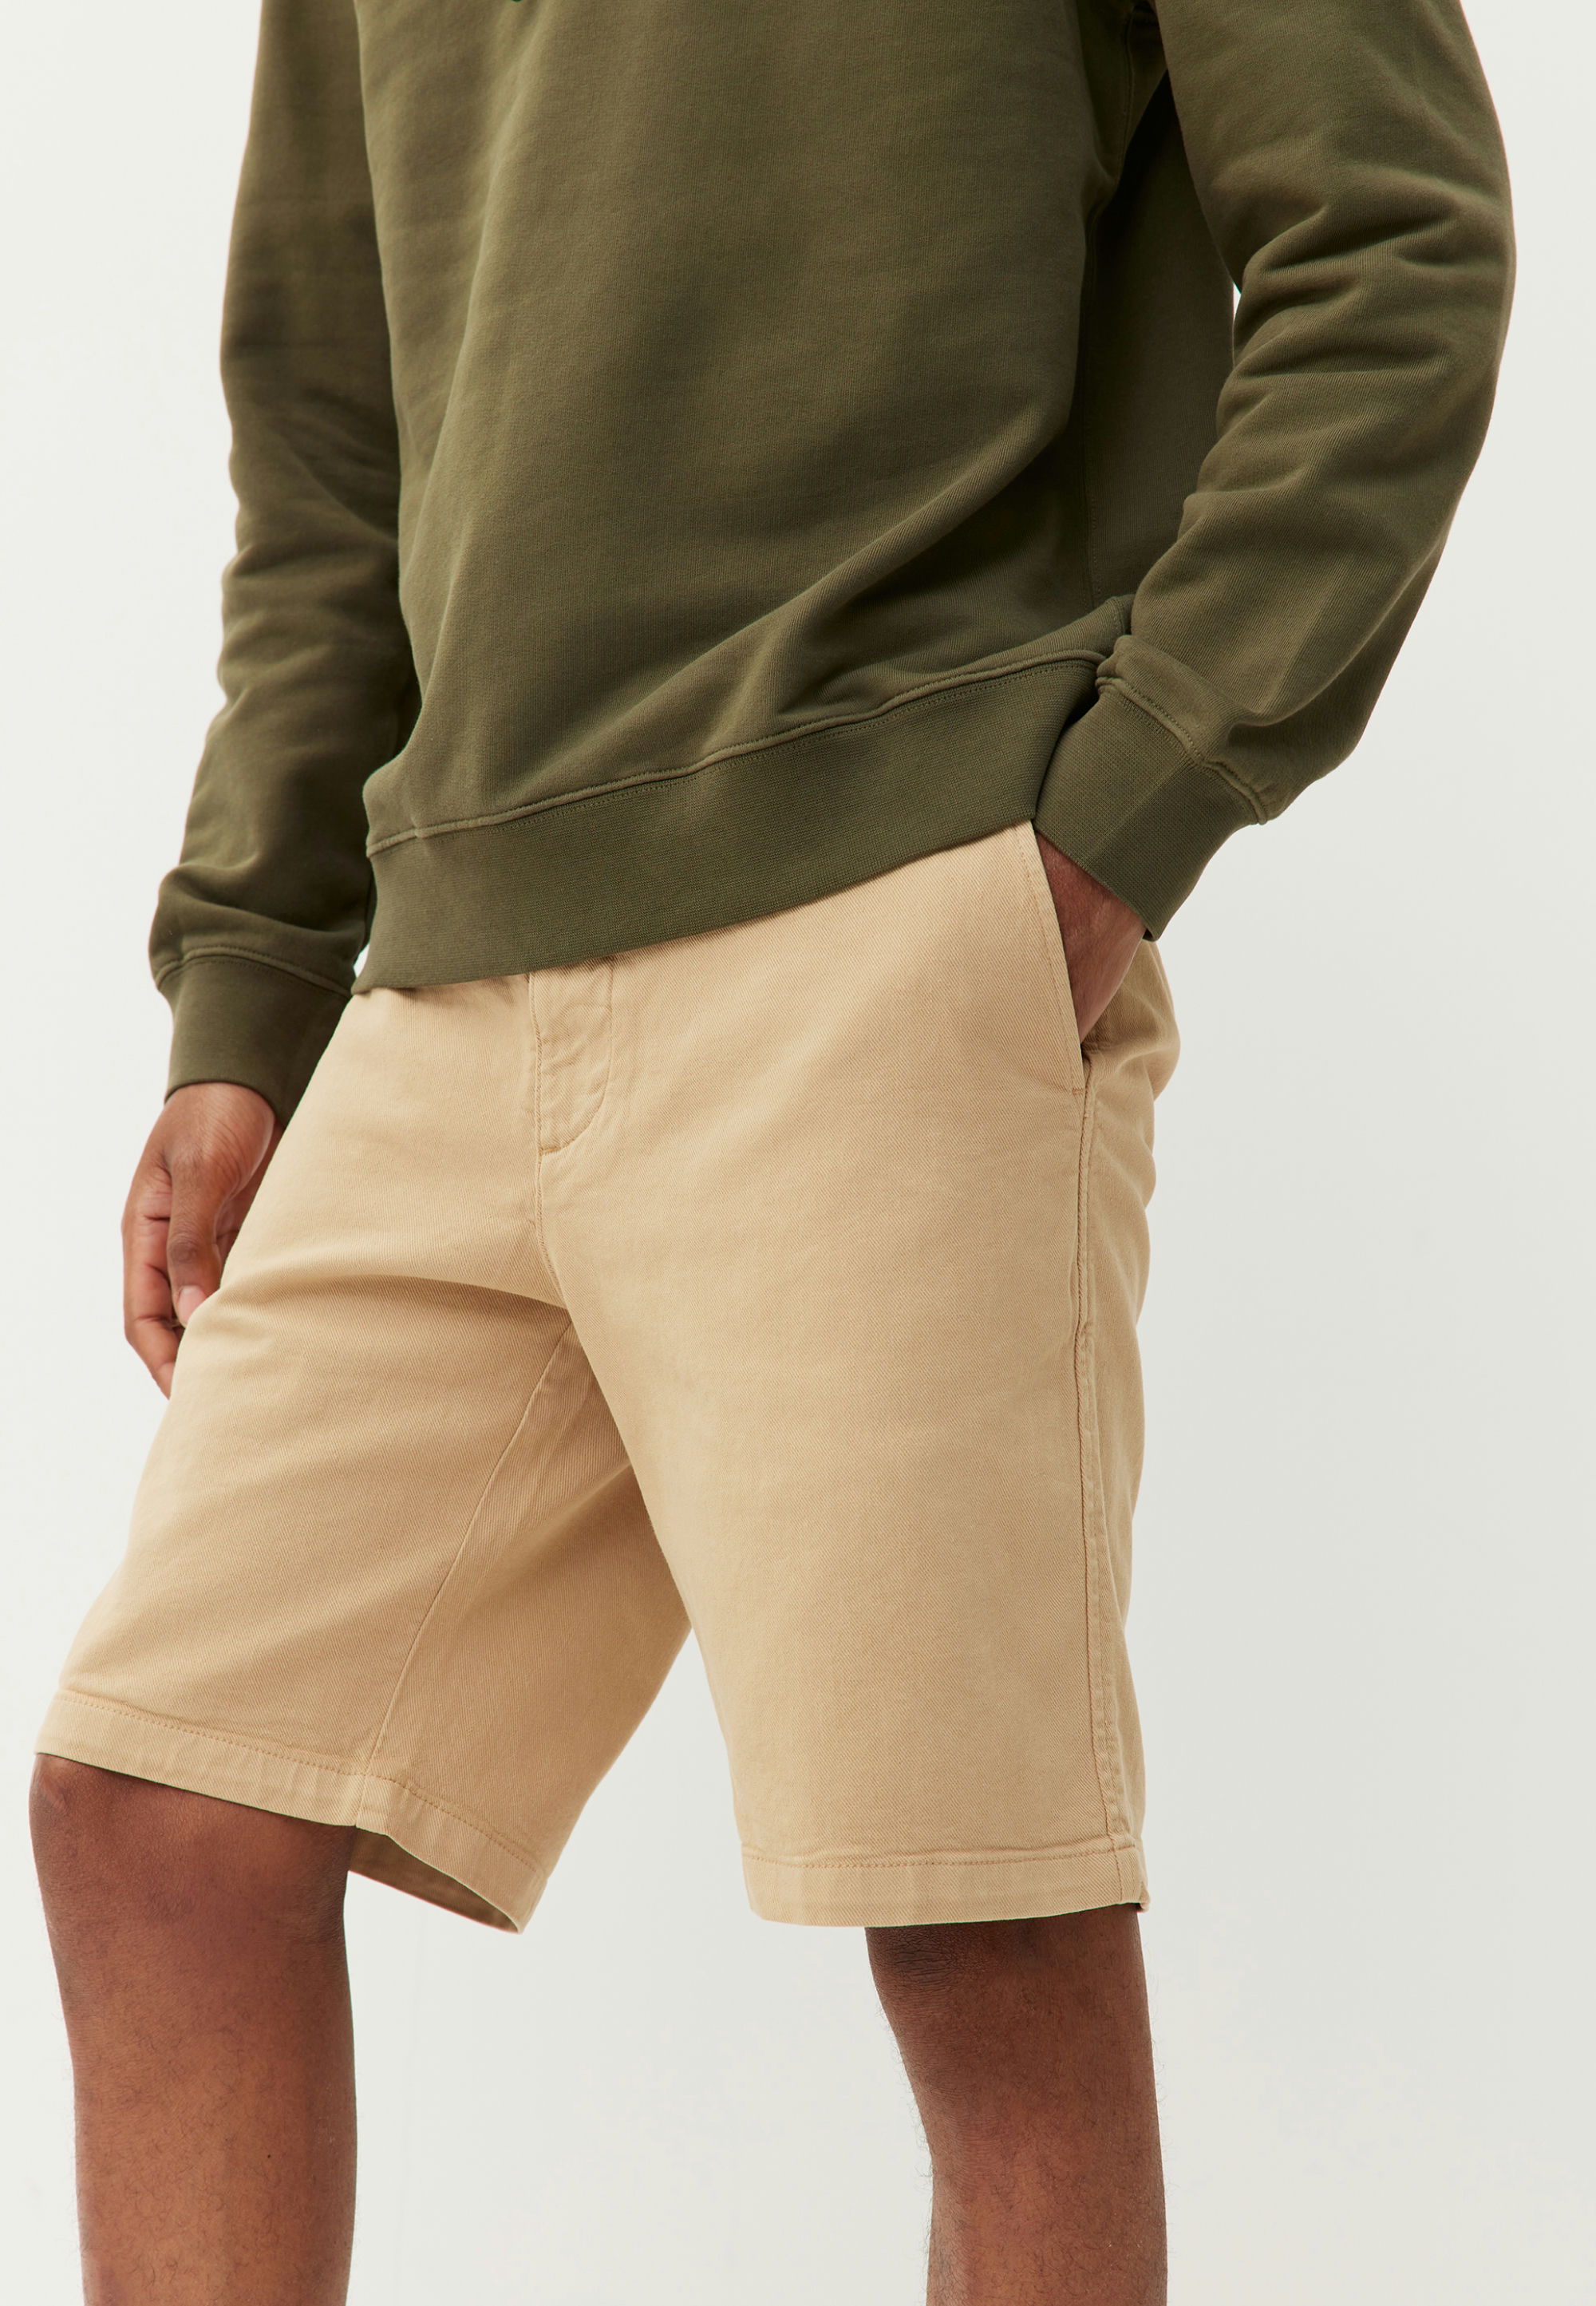
In June 2021, we released our first pair of shorts (or bermudas, much the same thing). Hard-wearing fabric made in France, double stitching at the crotch, reinforced waistband, a “jeans-style” button that won’t come loose, pre-washing to prevent shrinkage, roll dyeing for better colour retention, colourfastness tests in the wash... In short, we applied more or less the same recipe as for our trousers, and we thought we had every ingredient needed to make shorts that would last for years.
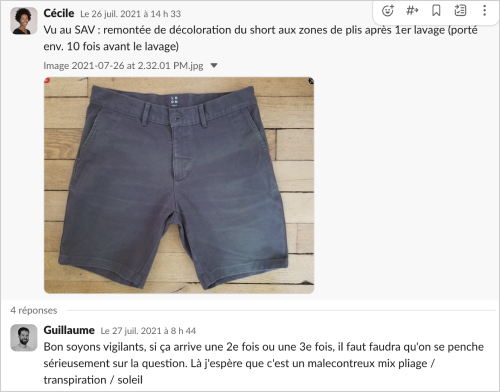
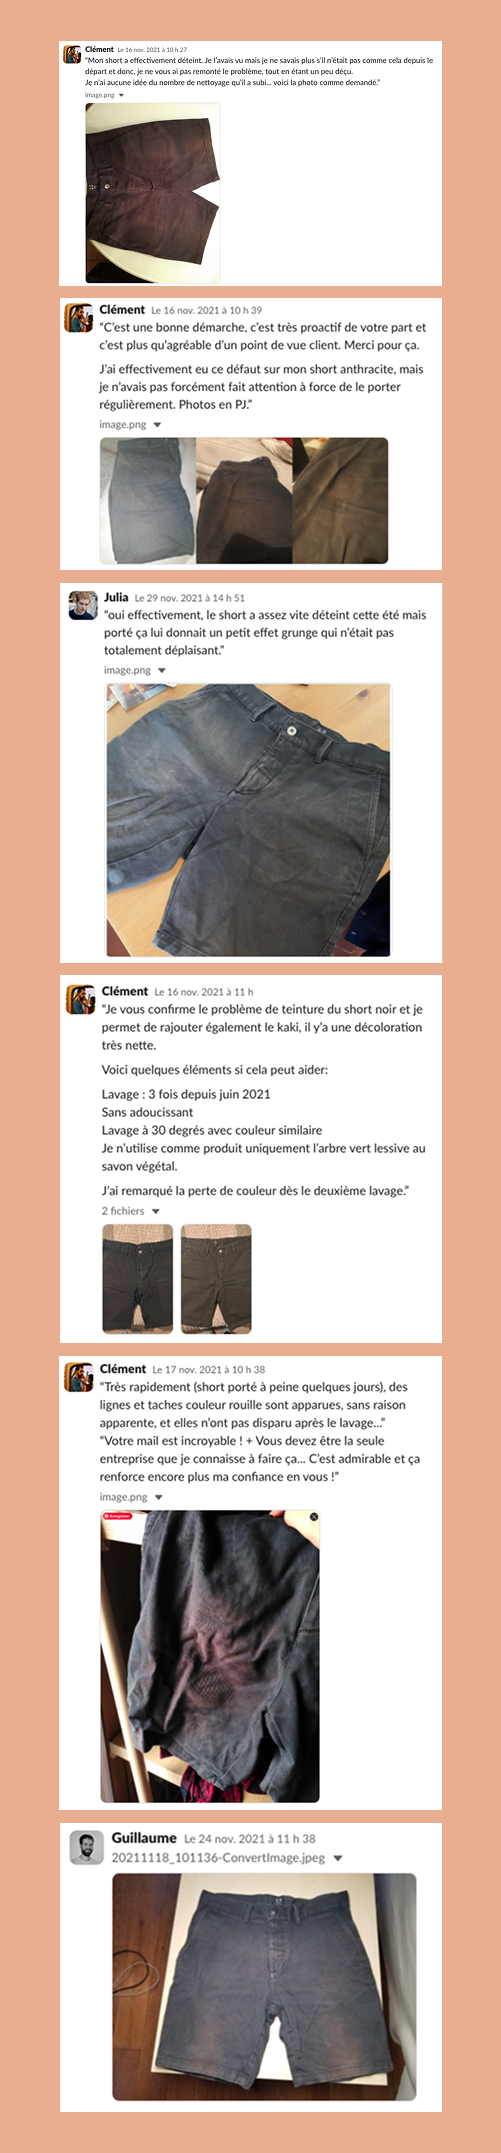
But barely a month after launching them, we got our first complaint:
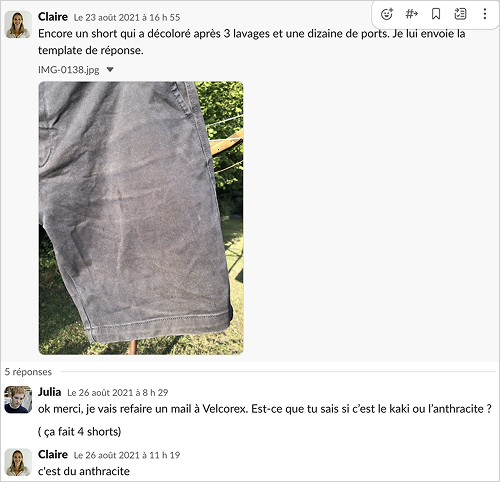
One complaint isn’t a big deal: it might just be an isolated case. Except that…
The kind of photo that gives any quality manager nightmares.
Not only were the shorts fading badly, they were also shifting colour! The charcoal grey, for instance, was turning reddish… By the sixth case, we started to panic and triggered our emergency procedure: we pulled the shorts from sale and commissioned laboratory tests to find the source of the problem.
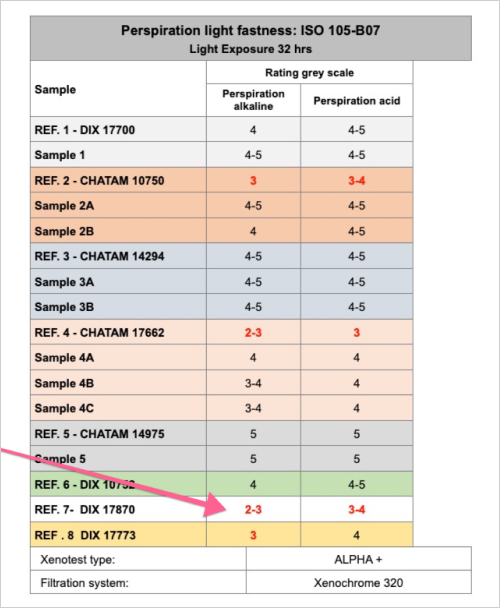
Our hypothesis was that this fading came from the combined effect of UV rays and sweat – rather as if our shorts were getting badly sunburnt. So we ordered a test in which our fabrics were exposed to UV rays for 32 hours while soaking in sweat baths (not real sweat, don’t worry). And the results hurt:
Ouch. Ooof. Ow.
Translation: our shorts really do have a serious fading problem when UV rays and sweat are combined, especially with so-called “alkaline” sweat (meaning sweat with a high pH).
Our shorts were in fact victims of what dyers call “golfer’s syndrome”: the collars of golfers’ polo shirts (they spend dozens of hours in the sun with sweat around their necks) tend to shift colour under the combined effect of UV rays and sweat.
For us, this was a disaster: we had sold hundreds of shorts that were going to fade badly.
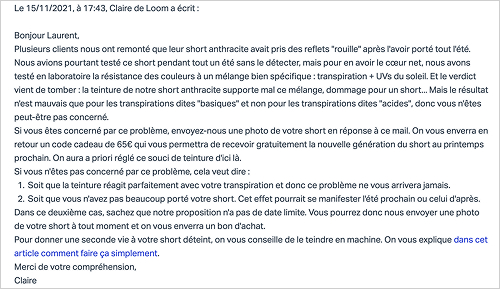
So we decided to organise a full product recall, rather like car manufacturers do when they discover a problem with the brakes or the airbags.
If you’d like to dye a pair of shorts or anything else yourself, here’s the article in question.
And the replies came in fast:
We realised the scale of the disaster... and also just how forgiving our customers are.
Over the following months, we worked with our factory to develop a dye recipe for shorts that would hold better. They improved it a little, but not enough. We had hit a wall: even after countless attempts, we couldn’t produce a dye that fully escaped UV fading. Time to go back to the drawing board.
The answer wasn’t a different dye, it was a different dyeing machine
At this point, one thing kept puzzling us: we had already made plenty of clothes that get exposed to sun and sweat… without ever running into fading like this. Starting with our t-shirts. So why now?
Our hypothesis: the fading actually came from the machines used to dye the shorts, which aren’t the same as the ones used for t-shirts.
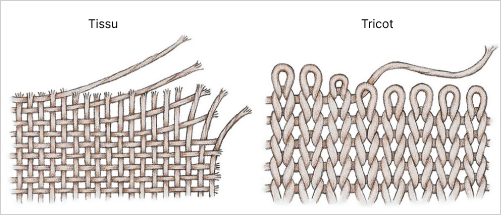
Here’s the thing: our t-shirt is knitted (to give it stretch), whereas our shorts are made from a woven fabric (to give them rigidity instead).
Image source: threadden.com
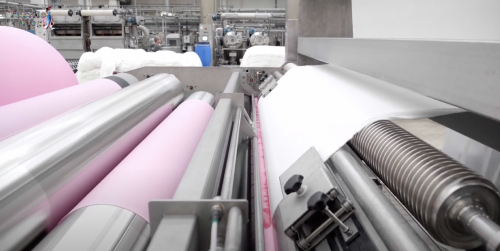
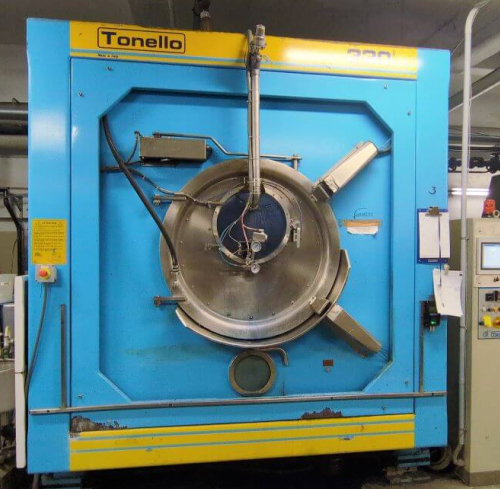
Because woven fabrics are fairly rigid, they can be dyed in so-called “continuous” machines: a system of rollers pulls them through a dye bath before they are wrung out and dried. It’s a fast, inexpensive process, with the advantage of using relatively little water and energy.
A continuous dyeing machine, like the one used to dye the fabric for our shorts (video here).
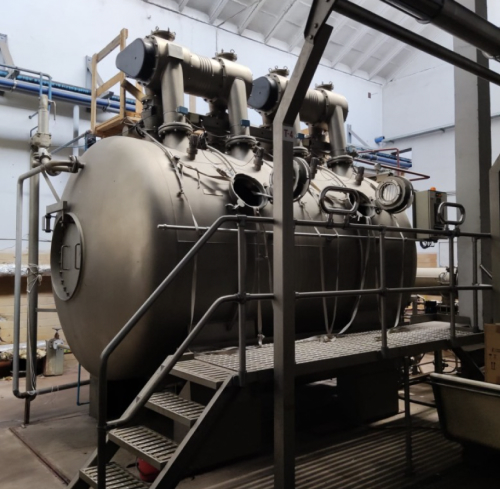
These machines can’t be used for knitted fabrics, though: they stretch more and would risk being pulled out of shape by the tension between the rollers. Instead, they are tumbled for several hours in an autoclave: a sort of large pressurised washing machine running at over 100°C.
An example of an autoclave, not to be confused with Captain Nemo’s little submarine.
Since the colours of our t-shirts hold up very well against UV rays and sweat, we wondered whether the secret lay precisely in that hours-long hot bath at high temperature and high pressure. Perhaps that’s what fixes the colours better than a quick dip in a dye bath between two rollers?
As it happens, there is a process for bath-dyeing garments made from woven fabrics too.
In factories it’s called “garment dyeing”. Instead of dyeing rolls of fabric and then making the garment, we do exactly the opposite: we make the garment and then put it in a dye bath, using almost the same machines used to dye the knitted fabric for our t-shirts.
Basically, “garment dyeing” means putting finished clothes into a washing machine (like this one) along with dye (video link).
That got us very interested. So we decided to have a “garment dyed” prototype made.
When it arrived, we noticed it had a more irregular, more lived-in look than our previous shorts. That’s normal: because these new shorts are dyed after being sewn, the dye settles into the irregularities of the seams, the bumps formed by the buttons, and the folds of the fabric.
Look closely and you can make out colour variations around the “hard points” (belt loops, pocket edges...).
And that’s good news for how they age: because the fabric’s appearance isn’t perfectly uniform, wear from machine washing or UV exposure shows far less.
All well and good, but do the colours of a “garment dyed” pair of shorts actually hold up better against UV rays and sweat?
How it holds up in real life
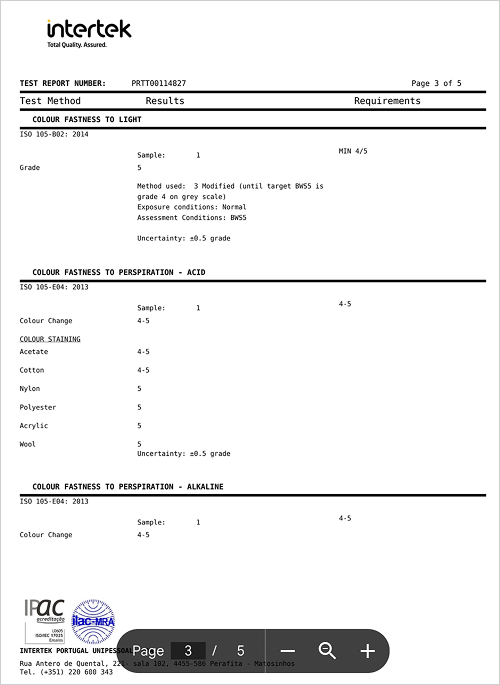
Before releasing our new shorts to the public, and after trying several different dye recipes, we ran a colourfastness test in the lab, which – fortunately – came back very convincing.
These numbers may mean nothing to you, but they are genuinely excellent results for UV and sweat resistance - it took us so long to get colours that hold up that we’re not about to change the ones on our shorts.
So we launched production of our “garment dyed” shorts, and 6 months later we started selling them… with a little apprehension: were these shorts going to end up fading too?
And here’s the beast!
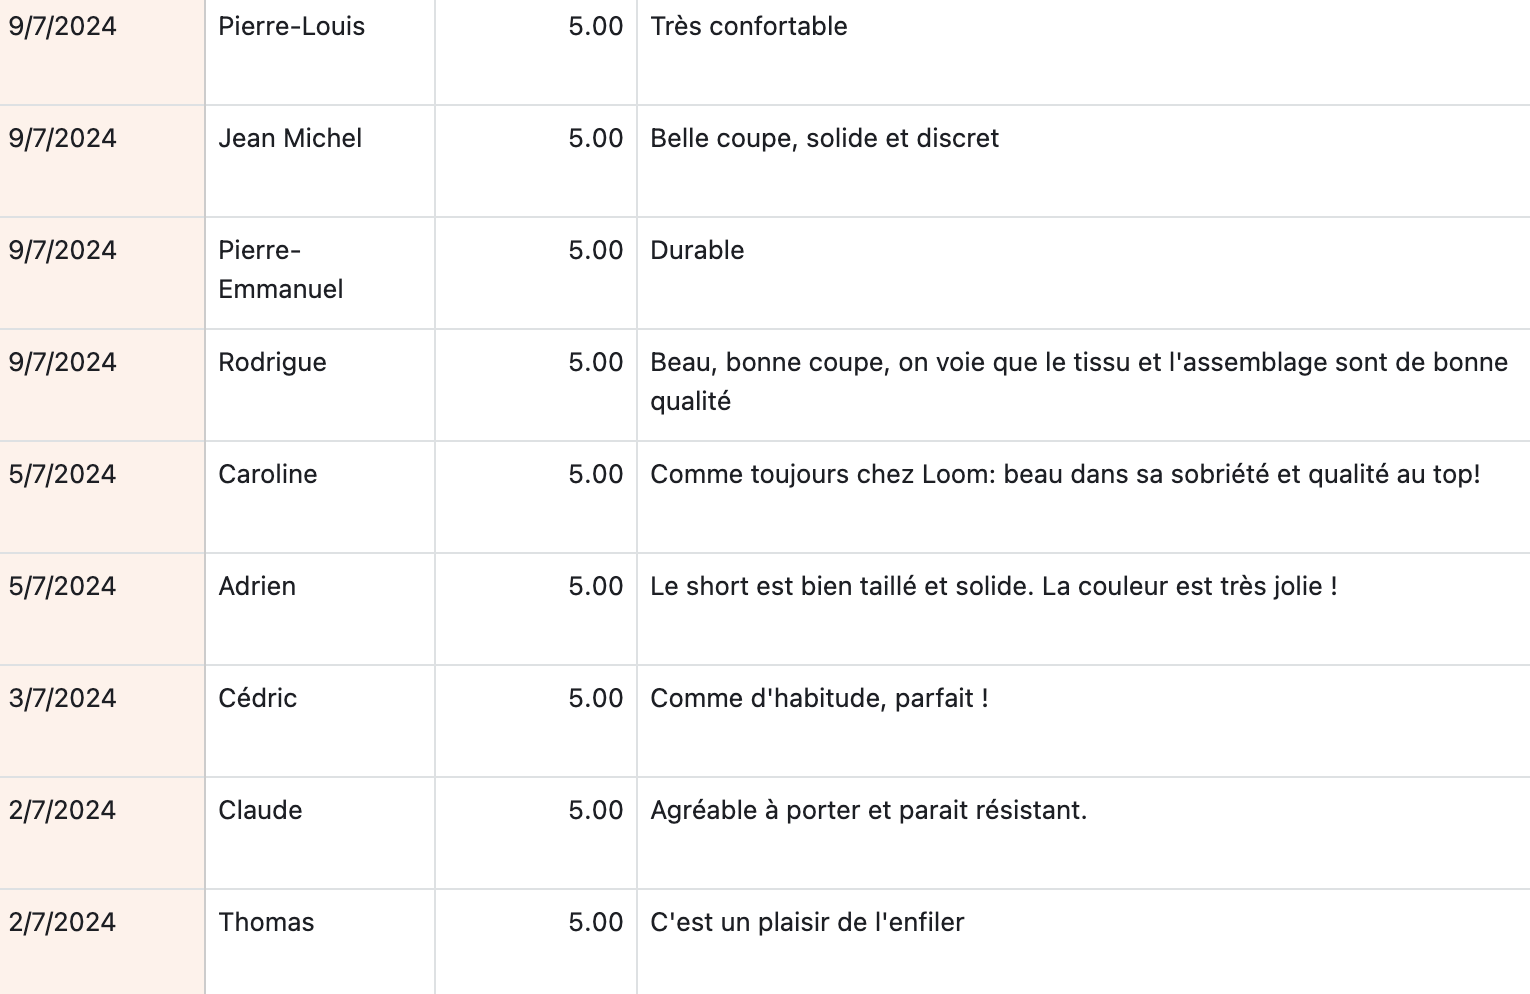
To find out, we had to wait at least a month, until our customers received an email asking what they thought of our products (long enough for them to have worn them a bit and put them through a first few washes). First sigh of relief: nothing to report! Our customers love the shorts.
Customer reviews of the shorts, one month after purchase.
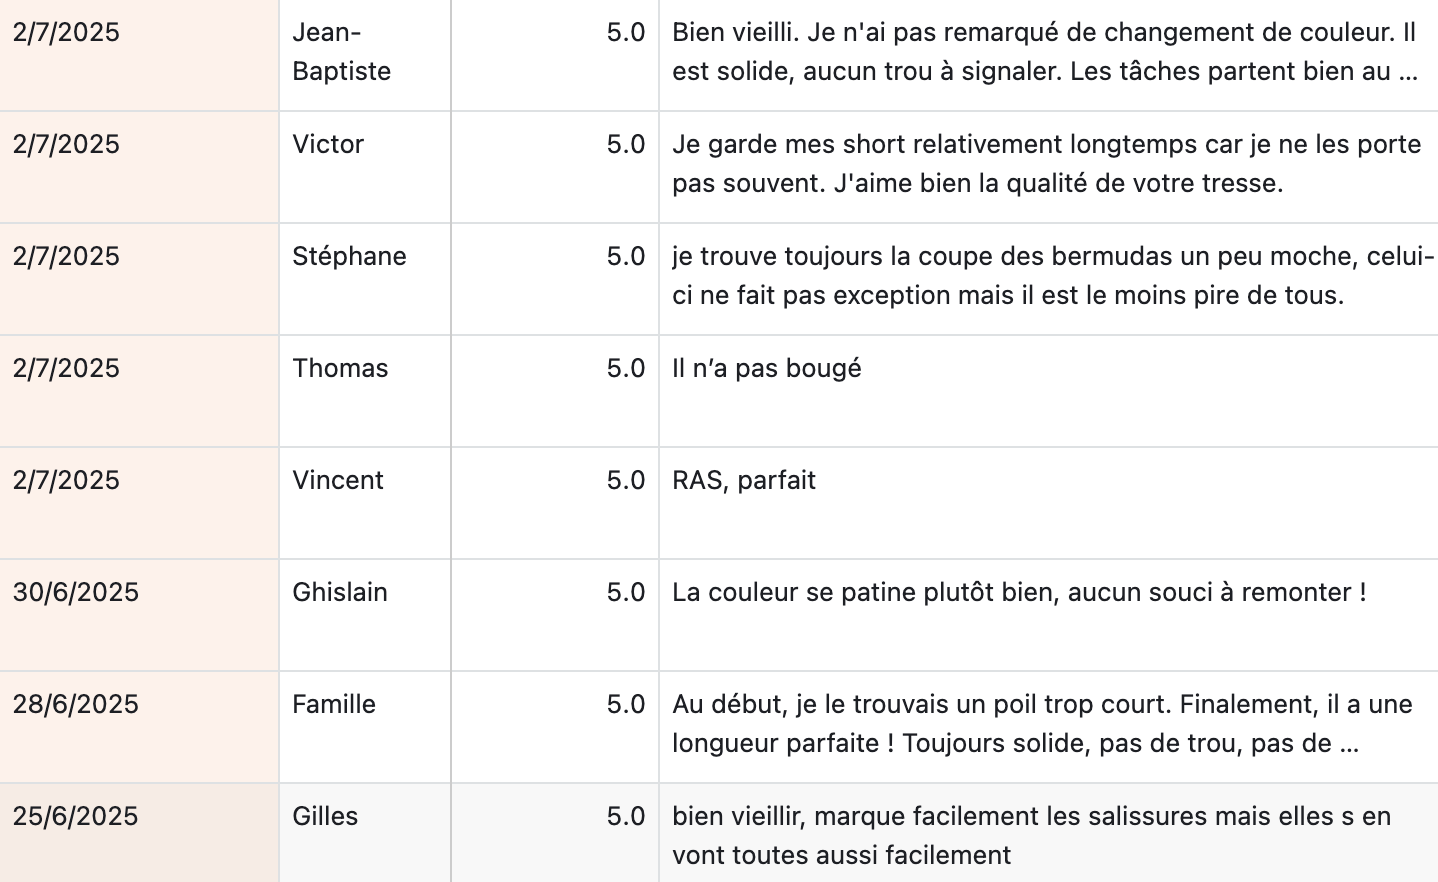
But the real verdict came in May 2025, when we got the first feedback from our customers one year after their purchase (the point at which we email them to find out how their clothes are ageing). And hallelujah: our customers are still delighted with the shorts. Across 65 reviews, they gave them an average rating of 4.7/5!
Stéphane certainly knows how to pay a compliment
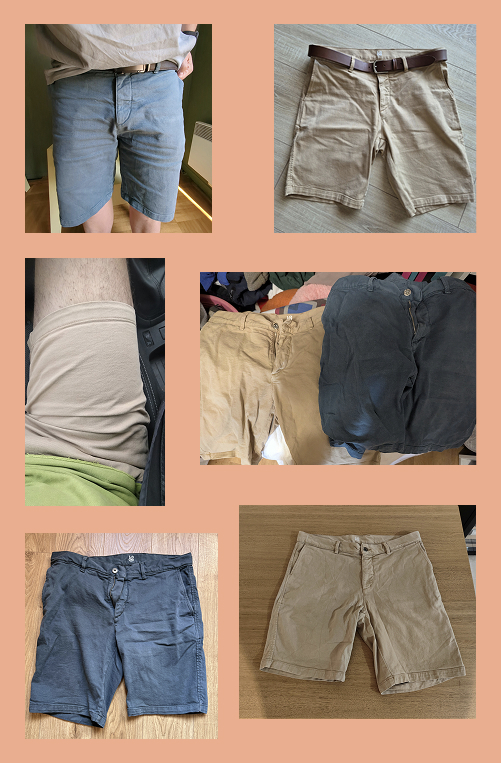
Admittedly, the colour of the shorts does shift a little...
Photos sent to us by our customers, one year after their purchase.
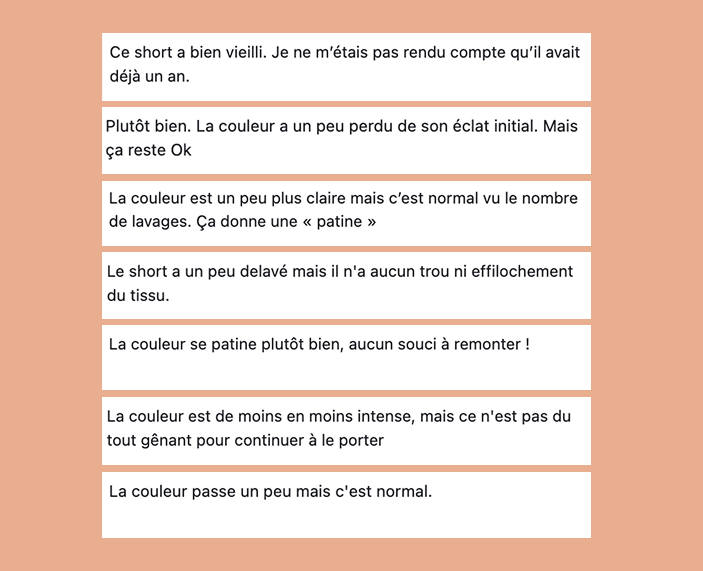
... but this time it takes on a lovely patina, not too strong and without shifting in tone.
A selection of customer quotes illustrating the point above. Kind regards.
Handy, but not magic
At this point you might be wondering: why don’t we use garment dyeing for all our Loom clothes?
Because this way of dyeing has its drawbacks too. First, as we saw above, it can produce a slightly irregular look: not remotely a problem on shorts – quite the opposite – but it can be on smarter garments, like chinos or a formal shirt. It’s also harder to manage at the factory: it costs a bit more (it uses more water and energy), there’s more waste, it’s difficult to land on exactly the right colour, and prolonged heat can sometimes weaken the garment.
In short, garment dyeing isn’t a magic solution. The further we get in our understanding of textiles, the more we realise how complex they are: to make clothes that last, you have to find the right industrial process for each individual piece.
And garment after garment, we’re also learning that you can’t have everything. To make shorts that don’t fade at all, we could go for a fabric containing polyester (colour is easier to fix on synthetics), as more and more brands do, but they would be less comfortable and less good-looking. Or we could have them made in Asia, where they use certain particularly aggressive (and dangerous) dyeing products that are banned here in Europe. In the end, every garment we develop is the result of a compromise across many dimensions: price, environmental impact, looks, ethics, comfort, and so on. For our shorts, the compromise we chose is organic cotton (a natural material), made close to home (in Portugal), that will take on a lovely patina over time.
Anyway, we hope you’ll like these shorts, that they’ll see you through many summers… and that they’ll age as well as you do.
Rather than throwing it away (or selling it on), you decide to give it to a charity that accepts donations, or to drop it into a collection bin (well done: only 30% of people do the same).
The collection bin: first stop on the journey.
Once collected, your t-shirt lands in a large sorting centre, where experienced sorters decide its fate by eye and by touch, depending on its condition, its composition and its potential resale price.
The sorting centre conveyor belt: in a matter of seconds, your t-shirt’s next life is decided (photo: Le Dauphiné Libéré).
From there, several things can happen:
Option 1: The cream (5%)
Your t-shirt is in great shape and can be resold at a good price in a second-hand shop. It’s part of what the trade calls the “cream” (remember that word, we’ll come back to it), in other words the 5% of collected clothes with the most value.
Option 2: The bottom of the barrel (45%)
Your t-shirt is in poor condition. It will either be “downcycled” (in other words, turned into rags or insulation) or incinerated to produce energy.
If your t-shirt isn’t worth much, there’s a fair chance it will end its days inside a wall.
Option 3: The soft middle (50%)
Your t-shirt is just a normal t-shirt: in good enough condition for a second life, but nothing special either. So it gets compressed into a big bale of clothes and sold to a foreign importer.
A warehouse full of bales of second-hand clothes: a sort of departure lounge for garments (photo : Amiratex).
Hang on. So the clothes we donate don’t go to people in need?
Well, it depends who you give them to:
Social-economy reuse organisations (for example Le Relais, which runs almost half of France’s 47,000 collection points). Here, your donation serves a social project: sorting and reselling the clothes creates jobs for people getting back into work, and the income funds their solidarity programmes.
Charities helping people in need (for example Secours Populaire, the Red Cross or Emmaüs): a small share of your donations may stock charity shops, where the most disadvantaged can receive clothes for free (through “solidarity wardrobes”).
Anyone else: then no, your old clothes won’t be helping the poor. They are feeding an ordinary commercial business1.
So no: most clothes will not be “given to the poor”, quite simply because the need is largely covered by existing donations. That said, if you give clothes of some value to charities, you are taking part in a system of solidarity: the “richer” the “cream” these charities collect, the more profitable they are, and the more people in need they can help.
That’s how it works in theory. Except that…
Today, the second-hand sector in France is on its knees. Some collection, sorting and recycling operators are losing money and starting to close down one after another.
What happened?
First, with the growth of platforms like Vinted, people tend to sell whatever has financial value and donate whatever has less. The “cream” left over for charities is getting thinner, which weakens their finances.
An Emmaüs campaign that posted fake listings on Vinted to remind people why donating to charity matters (photo: Label Emmaüs).
But the real blow to the second-hand business model is the rise of fast fashion and low cost: the value of the “cream” has shrunk structurally as Shein, Primark, Leclerc (a French supermarket chain) and the like have gained market share. Partly because the quality of clothes is going down, but mostly because the prices these chains charge for new clothes are so low that charities struggle to make any money reselling them. And the entire business model of collectors and sorters rests on reselling that “cream”. The cheaper the clothes, the less viable the second-hand sector. No wonder, then, that charities like Emmaüs are calling for regulation of the fast fashion and low-cost model.
There is a third, more circumstantial explanation for the second-hand crisis: export outlets are clogged. The African countries that traditionally bought our second-hand clothes are now turning to Chinese second-hand instead, and France no longer quite knows what to do with the millions of garments left on its hands.
But the second-hand crisis in France is only the tip of the iceberg: the sector is going through a global crisis, both economic and environmental.
Remember the t-shirt you dropped into the bin: half the time, it is sold to a foreign importer. But where exactly is the “abroad” your t-shirt gets sent to?
B) The struggles of the second-hand trade in Africa
In more than half of cases2, second-hand clothes end up in Africa, because (for now) buying Western second-hand there is cheaper than buying new.
And which African country? For your t-shirt specifically, that’s hard to know: after being sorted and re-sorted in several countries, the trail of French clothes goes cold. But if we look at all the clothes collected worldwide, here are the main African countries3 where they are likely to land:
These are global flows. For France, the main export destinations are Madagascar, Benin, Togo, Haiti… in short, the former colonies.
Once a garment reaches Africa, what becomes of it? To find out, let’s look at what happens in Ghana, the African country where the end of life of clothing has been studied most closely, thanks to The Or Foundation, an NGO very active on the ground.
The garment is unloaded at the port of Accra, the capital, wedged inside a bale of second-hand clothes, itself crammed into a container holding up to 400 of them.
The clothing importer is not a charity but a for-profit business: it sells the bale “blind” to a local trader known as a “retailer”, for around €180. This retailer (often a woman) then tries to sell the clothes one by one from a stall in the gigantic Kantamanto second-hand market.
This is what a bale looks like when a trader buys it. No way of knowing whether it holds anything valuable or not… a bit like a booster pack of Magic cards.
Kantamanto market in Accra, where 30,000 people work reselling, repairing and upcycling second-hand clothes (photo: Green Views).
In 60% of cases, the garment will be put up for sale, sometimes after a quick wash or a going-over with an iron. Otherwise, it may quite simply be… thrown away.
Why such waste?
If a garment gets exported to Africa, it’s because it is in fairly good condition: an estimated 95% of the clothes in these bales are “wearable”.
Yes, but… there are a thousand reasons why a “wearable” garment might not be “sellable”: maybe the seams have twisted a little, maybe there are already plenty of that style on the market, maybe it’s too warm for the climate, maybe the cut, the colour or the style is something nobody here likes, or maybe it needs washing and ironing but that just isn’t worth the effort.
If there were few clothes available in Ghana, far fewer would surely be thrown away. But with the flood of fast fashion cast-offs, so many pieces arrive every day that any given garment is more and more likely to go unsold… which leaves retailers in a critical financial position.
And if it is thrown away, what becomes of it?
Ghana does have official landfill sites, but they were quickly overwhelmed by the volume of clothes coming in. With nowhere to put the surplus, it is burnt or left in open-air dumps.
In Accra, the Old Fadama dump has doubled in size in 5 years (photo: Pouvoirs d’Afrique).
An abandoned garment can also be washed into a gutter by the rain, end up on the beach and start to decompose, with dramatic consequences: microplastics released, damage to marine life, the health of local people, the city’s economy…
Clothes on Ghana’s beaches, as seen in several recent TV reports (photo: Hugo Clément).
To sum up:
cheap new clothes flood Western countries
their value is too low for the local second-hand market, so they are sold abroad
there are so many of them that most go unsold in Africa
with no infrastructure to deal with them, they end up piling up in the environment
One clarification: the t-shirt you dropped into a bin in France is unlikely to end up on a beach in Ghana. That country mainly receives second-hand clothes from the English-speaking world. There are textile pollution problems in the countries France exports to as well (see the Cotonou lagoon, in Benin), though probably on a smaller scale than in Ghana. But nothing protects these countries from one day being swamped by the same textile pollution and the same economic crisis.
So how do we change this system?
II. The ideas that sound good but won’t save second-hand
Before looking at ways to turn this system the right way up, let’s start with the ideas that sound good but aren’t: they don’t solve the problem, and may even make it worse… yet they are the ones that keep coming up in public debate.
A) Bad idea number 1: Stop exporting second-hand clothes overnight
This is usually the first idea people come up with when they see these mountains of textile waste: Western countries should simply stop exporting their cast-offs, or African countries should ban them from entering. In reality, it’s a very bad idea.
First, halting exports overnight would wipe out a whole section of the economy, leaving tens of thousands of people in Africa with nothing to live on.
But above all, it would create another problem: “We are 100% certain that if second-hand exports stopped tomorrow, they would be entirely replaced by new fast fashion, which would be even worse”, say the people running The Or Foundation. In Kantamanto market, historically reserved for second-hand, stalls selling new fast fashion clothes are multiplying. One of the few things holding back a massive influx of cheap new clothes into Africa today is the dominance of second-hand, which is still cheaper.
That said, in the medium term, we do need to export fewer clothes and manage their second life better at home.
B) Bad idea number 2: Sort better before exporting
The pollution of African beaches by second-hand clothes is often boiled down to a question of “poor sorting” in France. As we saw above, the problem is not that exported clothes aren’t sorted carefully enough: the reasons a garment gets discarded in an African market are so many and so varied that “sorting better before exporting” is impossible. The real problem is that there is no longer enough value in the clothes collected to keep every link in the chain in business.
Blaming the people who sort clothes for the consequences of the fast fashion boom is unfair… but it does conveniently draw attention away from the real source of the problem. When the bath is overflowing, blaming the people with the mop is a way of not noticing that the tap is on full.
C) Bad idea number 3: Recycle everything
It may seem obvious at first: rather than exporting, why not recycle in France and turn our old clothes into new ones?
Unfortunately, the economics of recycling are very tricky: fibres recycled from old clothes are generally more expensive and of lower quality than their virgin equivalents, and the recycling industry remains fragile. Witness the recent troubles of Renewcell (even with H&M behind it), Carbios and Soex. The result: worldwide today, less than 1% of old clothes are turned into new ones.
We can of course fall back on “downcycling”, for example turning old clothes into rags or insulation. But even then, it isn’t easy for local downcycling plants to find buyers: their rags and insulation can quickly end up costing more than virgin equivalents made on the other side of the world. To keep their business model afloat and encourage them to grow, investment and subsidies are needed.
It’s better than nothing, and supporting such plants is vital. But if we want to reduce the environmental impact of textiles, downcycling should be an option only for clothes too damaged to be worn. We should be doing everything we can to make sure that clothes that are still wearable get worn again, rather than turned into rags. And there is only one way to do that: rein in fast fashion so that it stops competing with second-hand.
To go back to the bath metaphor, betting everything on recycling is like putting all our money into treatment plants for the water spilling over the edge… instead of turning off the tap, or at least turning it down. Wouldn’t it make more sense to turn clothes into rags only once they have been worn for years, to the point of falling apart?
There is a long road ahead to get there, but change is far from impossible.
III. A user’s guide to a truly circular textile economy
A) Make the money follow the clothes
As long as we keep sending so many clothes to Africa, there is no avoiding a large share of them becoming waste. So the infrastructure to deal with them needs to be built locally: recycling plants, landfill sites, working sewers, wastewater treatment, incinerators. But there is a money problem: on one side, local people depend on this economy; on the other, the states are not rich enough to treat the waste.
The same goes for electronic waste from Western countries, which ends up in Ghana, but also in India, Pakistan, Vietnam… (photo: the Arte documentary “The Light Bulb Conspiracy”)
The lack of money also creates critical safety problems. In January 2025, Kantamanto market burned to the ground, for want of an effective fire prevention and response system. Another danger: most of the goods are carried by the kayayei - women “head porters” - who thread their way through the market’s narrow, crowded aisles with loads of up to 55kg balanced on their heads. This hard, dangerous work could be replaced by trolleys… if there were enough money to widen the aisles.
Tragedies happen too, when a bale falls onto the baby the kayayei carry on their backs (photo: The OR Foundation).
In short, these countries need money to deal with our cast-offs. And as it happens, there is already a mechanism that (in theory) funds the end of life of clothing: EPR, or Extended Producer Responsibility.
EPR is a system that makes companies responsible for the end of life of the products they sell: basically, it’s the polluter-pays principle in action. If a brand puts a garment on sale on the French market, it has to pay a few cents to an “eco-organisation”: ReFashion. With the money collected, this body gives financial support to sorting operators, funds a repair bonus for clothes taken to an alterations shop, runs campaigns to raise consumer awareness, and so on.
The problem: the foreign countries that receive our old clothes never see a cent of that money, because it is spent exclusively within France.
And yet, if we are talking about “Extended” Producer Responsibility, wouldn’t it be only natural for those who deal with most of our textile waste to get the means to build the infrastructure they need, so that clothes stop ending up in their rivers and on their beaches?
In other words, we should make sure that EPR money follows the clothes when they leave France. This “worldwide EPR”, or Global EPR, is a recurring demand from the NGOs and countries that depend on the second-hand trade.
B) Rein in fast fashion… and make it pay
Being fairer to other countries matters. But what we would really like, in the long run, is a second-hand economy that works in France, without shipping so many clothes to the other side of the world.
To understand how to get there, we need to rewind a little. Why did a textile EPR scheme have to be created in the first place, in other words why did brands have to be asked to pay for the end of life of their clothes?
Historically, the second life of clothes never needed subsidising: when clothes were still scarce and worth more, people repaired them and wore them until they fell apart, or handed them down within the family. And when the wealthy parted with their clothes, buyers were easy to find. In the Middle Ages, that was the job of the old-clothes dealers, the “fripiers”: they not only resold clothes but also repaired, cleaned and restored them. The business worked wonderfully: in the 19th century, the Carreau du Temple market in Paris had more than 1,500 of them.
It was from the 1980s and 90s, with the arrival of low-cost and fast fashion brands, that the second-hand business model in France stopped working. So in 2008 the famous “EPR scheme” had to be created: the state asked brands to prop up the second-hand economy financially.
On paper, it’s a great system.
The catch is that every brand pays the same eco-contribution, whatever its business model: around 5 cents per garment, an amount set to rise in the coming years to keep up with new needs. That’s unfair: fast fashion and low-cost brands are the ones destroying the profitability of the second-hand sector, so they should be the ones bearing the cost, through higher eco-contributions. That would honour the polluter-pays principle the scheme was built on, and push these brands to rethink the way they produce and sell.
How do we get there?
First, the governance of the EPR scheme needs an overhaul. As we saw above, it is run by an eco-organisation, Refashion. Its remit is set by the public authorities, but in practice it is funded, steered and controlled… by the companies that put the most clothes on the market. Under those conditions, there is little chance of Refashion asking low-cost and fast fashion brands for a bigger eco-contribution. For this body to act in the general interest first, its independence needs strengthening, for instance by creating an independent regulator, as recommended in this recent report by the Inspection Générale des Finances (the French finance ministry’s audit body).
But above all, it will take real political courage to significantly raise the eco-contributions fast fashion pays… And fortunately, that is starting to happen. Notably with the so-called “anti-fast fashion” law, passed unanimously by the National Assembly (the French lower house) in March 2024, which introduces a bonus-malus system into the EPR scheme of up to €10 per garment.
The law has still not been examined by the Senate, and there is a real risk of seeing it emptied of its substance. Hardly surprising: low cost and fast fashion are lobbying hard, going as far as hiring former ministers and leaders of MEDEF (the French employers’ federation). Fortunately, many players in French fashion, the second-hand ecosystem and NGOs are fighting to get it passed.
And yet the end of life of our clothes could be a lot cleaner if there were no more (or far less) fast fashion and low cost. If our clothes were worth something again, we would relearn how to look after them and how to repair them (or have them repaired): we would re-dye faded shorts, re-knit the broken seams of our sweaters, cover the holes in our sweatshirts with pretty embroidery…
Once worn threadbare, our clothes would become rags, insulation or cushion stuffing. And if we decided to part with them while they were still in good shape, they could easily be resold in local second-hand shops, because they would be worth enough to keep everyone in the chain in business: collectors, repairers and shopkeepers.
In short, an economy that cuts waste, creates jobs locally, spreads wealth to every link in the chain, builds know-how and sovereignty… as visions of the future go, that one is rather cheering, isn’t it?
P.S. We need you
France is working on a method for environmental labelling of textiles that has one great merit: it penalises fast fashion’s incentives to overconsume and rewards more responsible business practices. But there is a risk that Europe will throw the text out and impose a less favourable method. Help us defend the French method by signing this online petition!
Notes
1 In some cases, collected clothes are exported abroad without being sorted: this is known as “original” export. The main countries France exports to are, in order: Tunisia / Belgium / the United Arab Emirates / Pakistan (source). There, the clothes are sorted and graded: the “cream” is re-imported into France (or other Western countries) to be sold in second-hand shops of the Kiloshop type. So why the round trip? It is (as usual) a question of money: in Pakistan, labour is far cheaper. In the end, “original” export offshores the sorting stage to low-cost countries. And there are quite a few companies of this kind: they account for nearly half of French clothing exports (Source: Refashion 2022 report: “Nearly half of these flows are not tracked by Refashion because they are exported by non-contracted operators”). To dig deeper, watch the documentary Very Bad Fripes.
2 To be more precise: second-hand clothes are sometimes first sorted in centres in other countries, such as Belgium or Pakistan, which then send them on to Africa. But in the end, more than 50% of French exports finish up in Africa. Source: our reworking of customs figures.
3 Analysis based on world trade statistics (source).
Making a bath towel had been on our minds for a while, because we couldn't find many that met our four key requirements:
A little over a year ago, we decided to get started. To figure out what our towel should look like, we created a survey with one central question: “What’s the problem with your towels in general? Why do you end up stopping using them or throwing them away?”
After combing through your hundreds of responses, we realized the towel of your dreams was…
soft: 50% of you complained about towels that are too scratchy
durable: 20% of you mentioned holes or fabric that wears out too quickly
absorbent: 20% of you told us about towels that don't dry you off well enough
All of that means that what you really wanted was one thing above all else…
A nice, thick towel
That’s right, it’s the thickness that allows it to:
provide that plush, cozy feel
slow down the appearance of holes or fabric wear
absorb water better
We therefore chose to manufacture a towel with a high weight of 700 g/m2, which looks exactly like this:
In the industry, it is generally considered that an entry-level towel has a weight of 200 to 400 g/m2, mid-range goes from 400 to 600, and high-end starts at 600. According to hotel linen suppliers, 700 g/m2 is actually “luxury hotel” quality:
Probably the only thing we have in common with the Ritz.
But density isn't everything; there are other factors that go into making a quality towel:
To ensure it’s soft, we chose combedcotton, meaning we kept only the long, well-aligned fibers (much like well-combed hair).
For absorbency, we opted for fairly large loops, 4.7mm high. That’s right: loops increase the surface area between the cotton and the water, allowing it to absorb moisture much faster.
We pre-washed our towels at the factory so you can use them right away (and to ensure they don't shrink in the first wash).
Finally, we chose to use organic cotton (not to be confused with the Oeko-Tex label, which only guarantees that pesticide residues have been removed from the final product).
And all of this…. Made in Portugal.
As we explained earlier, we wanted our production to be as local as possible. But there was one thing we couldn't manage: manufacturing this towel in France. You might be thinking that’s a shame, since there are still home linen manufacturers in France... Surely companies like Lin Vosges, Blanc des Vosges, or Garnier Thiébault know how to make terry towels, right?
Customer feedback from our bath towel survey.
That’s what we thought too, but after looking into it, we quickly realized otherwise.
Why there are no more made-in-France towels
In reality, French manufacturers (including those mentioned above) primarily produce bed linen (sheets, essentially), not bath linen. To quote Blanc des Vosges: “We prioritize carrying out every stage of our products' manufacturing in the Vosges whenever possible [...]. Unfortunately, the expertise for manufacturing terry cloth barely exists in France anymore.”
That’s right: making terry towels requires a very specific machine to weave the small loops—a loom with two beams (one for the base of the fabric, one for the loops).
For this reason, towels sold in France come from countries that have developed or maintained this expertise (unlike France) and possess these machines, such as Pakistan, Turkey, or India:
Cotton terry towel imports by country in 2023 (in tonnes) according to French customs.
Yet, not so long ago, France still had a major terry towel industry. We even had the largest manufacturer in all of Europe: Jalla. It seems it even became a household name, like Kleenex or Frigidaire… Back then, people would “dry off with a Jalla.”
A 1953 ad for Jalla highlighting its softness, durability, and absorbency. It was worth conducting a survey: in 70 years, expectations haven't changed.
The Jalla factory was an industrial empire, known for its large company town… which today looks like this:
Jalla factory site in Nieppe: an abandoned industrial wasteland (the Jalla brand still exists but no longer manufactures in France).
In short, the classic story: starting in the 70s and 80s, the opening of the textile market to global competition proved fatal for terry towel manufacturers. Today, only a few factories remain in France (such as Yves Delorme’s) that produce very specific towels: those with complex patterns, which require weaving on a "Jacquard"loom.
Some brands (like Embrin for example) still manage to have linen towels manufactured in France by using a “honeycomb” weave that can be produced on a standard loom. If you aren't concerned about fluffiness and Made in France is important to you, linen towels are an excellent alternative to cotton ones in terms of quality.
Will we ever be able to manufacture our Loom cotton towels in France? We would love to, because in theory, we could release them at a reasonable cost: compared to a shirt or a pair of pants that require dozens of minutes of manual sewing, a towel takes very little time to make. In other words, the share of labor costs in manufacturing is quite low compared to machine or energy costs, which makes this product a good candidate for production in France (to learn more about this, we wrote an entire article here). So, we’re putting a message in a bottle: is there a French textile factory planning to reinvest in looms for terry towels? (Otherwise, who knows, maybe one day, at Loom, we will set up our own factory ?).
But in the meantime, our thick, organic cotton towel, made in Portugal, is available in 3 colors on this page.
Ta-da!
The 50x100 cm is €20 and the 70x140 cm is €30. Prices that aren't too high because, as usual, we keep our margins small (if you want to know why, read this page).
But before we go, we wanted to tell you one thing. If 50% of you find your towels a bit scratchy, it doesn't necessarily mean they are worn out or poor quality: it might just be because not many people know how to wash them properly. We’re going to take a few minutes to explain how to care for them so they stay nice and fluffy.
How to keep your towels fluffy
For several years now, we’ve been helping customers who complain to Loom’s customer service that their clothes have become scratchy over time. By looking into this issue, we’ve learned a few things that apply even more to the world of bath towels.
Fabrics can become scratchy due to two things:
1/ Washing
Successive washes cause a buildup of detergent, fabric softener, or limescale residues on the fibers. So, to keep your towel fluffy, you need to get rid of these residues. To do this, you must:
not use too much detergent
NEVER add fabric softener (yes, it’s quite counter-intuitive, but fabric softener coats the cotton fibers and makes them lose their absorbency).
But above all, there is a magic solution to get rid of these residues:
Yes, white vinegar. When you run a load of laundry, pour a glass of white vinegar into the fabric softener compartment: it will dissolve limescale and detergent buildup (if you’ve ever cleaned a kettle with white vinegar, you know it’s magic against limescale).
The fabric softener compartment is usually the one with a blue plastic tip and a little flower icon. You probably already knew that, but just in case…
2/ (Most importantly) drying
Actually, it’s during the drying process that your towel is most likely to become scratchy. And that comes down to chemistry.
As water evaporates, the cellulose molecules (which make up cotton) rearrange themselves to form longer molecules, which creates stiffness. This is exactly the same phenomenon that causes wrinkles in cotton fabrics.
Mini chemistry lesson: when water evaporates, water molecules (H2O) give way to new hydrogen bonds between the cellulose molecules (the little orange lines). Illustration credit: Laghi I.
Very scratchy (sandpaper level) : you dry your towel on a drying rack, a clothesline, or a towel warmer without shaking it out before or after
A bit scratchy but okay : same as above, but you shake it out well before and after
Fairly soft : you dry it on a drying rack outdoors and a light breeze keeps the towel moving
Fluffy: you dry it in the tumble dryer
Ultra-fluffy (kitten-soft level): You dry it in the tumble dryer with dryer balls, which toss the towel around even more
Of course, tumble dryers consume a lot of energy, so they aren't great for the planet. We'll leave it to you to decide between your comfort, your environmental conscience, and your electricity bill ;-)
One last tip for the road
As is often the case, we learned a lot while developing this product: about what makes a quality towel, about French industrial history, and about care methods. We hope you’ll go to bed a little smarter tonight, too.
But after reading your survey responses, we realized there was one last thing we could teach you: how to tie your towel around your body so it doesn't fall off.
Feedback from a customer who had a slightly awkward moment when the neighbor across the hall rang the doorbell to borrow some salt.
Dear François, successfully tying a towel around your body isn't about the towel, it's about the technique. To do it, wrap the towel around your waist and then fold the top edge down. If you missed that viral TikTok video, here is how to do it on video.
1. The (sorry) state of the clothing industry in France
If you own a hundred or so garments, you should count roughly… three labels. Maybe a pair or two of socks, perhaps a piece of underwear or a sweater. That’s right: only 3% of the clothes sold in France were made in France1.
In other words, the clothing industry in France, the one that dresses us every day, has now all but disappeared2.
And yet that’s not really what you read in the papers. Every now and then you hear about a “textile revival”, supposedly with more than 100,000 jobs3 (a figure that is even said to be rising4) and clothing exports climbing above 14 billion euros5… Unfortunately, these figures are misleading.
Look closely and you’ll see that these 100,000 jobs include the employees of every company whose “main activity” is “textile manufacturing, garment making, leather and footwear”. But among those companies, how many actually make the clothes we wear every day? Well, not many. Here is how the 109,000 jobs in the clothing, textile and leather sector break down6:
So we have:
42,000 jobs in the leather industry, which accounts for most of the job growth reported (+14,000 jobs since 20067). But these companies make hardly any clothes: to caricature slightly, they mostly make luxury handbags, which aren’t much use for getting dressed in the morning8.
36,000 jobs in the textile industry proper, in other words fabric manufacturing (spinning, weaving and so on). But this industry is largely geared (two-thirds of it9) towards technical textiles (car seat covers, workwear, fabrics for furniture or the medical sector), as well as upholstery fabrics and household linen. Happily, this technical-textile ecosystem is fairly dynamic in France, but it makes almost no clothing.
31,000 jobs in garment making. But look at the detail and the biggest companies listed in this category (here or there) are actually brands that have most of their clothes made abroad: these aren’t jobs for seamstresses and tailors, but mostly for office staff and buyers, so nothing to do with a local industry. As for the rest, it’s mainly sewing workshops that produce for the luxury industry (which accounts for up to 90% of their customers). So among these 31,000 employees, very few are actually making clothes...
In fact, out of these 109,000 jobs, only a few thousand (probably no more than 10,00010) are genuinely dedicated to dressing France day to day.
Leave out the sewing workshops, which now work mostly for luxury brands, and France is left with only around fifty small factories that really make clothes: a handful of spinners, weavers, knitters and dyers working in niche segments (we’ve listed them in this document, feel free to add any others you know of). By way of comparison, Bangladesh has more than 8,000 factories dedicated to clothing11, almost 200 times more…
And these are the same factories you see over and over again in TV reports to show that clothes can still be made in France. They often carry the “Entreprises du Patrimoine Vivant” label (a French state label for heritage craftsmanship), and rightly so: they are the guardians of know-how that is disappearing by the day. But for how much longer? Many of them are in serious difficulty today, like Velcorex in the Vosges mountains, in eastern France, or Lemahieu in the Nord département, in northern France12.
And what about those 14 billion of clothing exports sometimes mentioned in the media, where do they come from? Part of it is down to luxury, but otherwise it’s mostly re-exported clothing: the big French brands (Kiabi, Décathlon and so on) store clothes made abroad in their French warehouses, then ship them to their shops abroad to sell them there. As INSEE, the French statistics office, points out13, 75% of French textile exports come from imports.
In other words, France’s everyday clothing industry has almost entirely disappeared… and many of the remaining factories are in serious trouble. In short, we have almost completely offshored an industry that covers what you’d think was a fundamental need of the population: getting dressed.
Why did we lose our industry? Mainly because a garment is… soft.
2. Why France no longer has a clothing industry
The textile industry makes soft, flexible objects, and that changes everything. Why? Because when materials are soft, nobody knows how to replace the human hand with a robot.
A quick reminder: making a fabric or a garment takes a certain number of steps:
All of these steps use machines, of course. But when you get to the last one, garment making, the machine becomes rather… modest:
The biggest machine in a sewing workshop… is the sewing machine.Photo credit Rio Lecatompessy
Yes, the sewing machine, and it takes a skilled seamstress or tailor to operate it. So unlike rigid metal or plastic parts that robots can grab and move around, only humans can put pieces of fabric together and sew them. It’s not for lack of trying to automate it: history is full of failed attempts to build robots that would do the sewing instead of humans. The Japanese state itself invested more than 100 million dollars in the idea in the 1980s14. Even DARPA (the US defence research agency) has invested in robotics start-ups to sew t-shirts15. But every time, these attempts came to nothing.
There’s no way around it: making a garment takes human labour, especially at the sewing stage. Sewing a t-shirt, for example, takes 5 minutes. For a pair of jeans, it’s almost impossible to get below 15 minutes16. So clothes were the perfect candidates for offshoring: they are easy to transport, they don’t perish and, since they need a fair amount of labour, there was a huge competitive advantage in moving production to countries where wages are very low.
So from the 1960s and 70s onwards, as soon as container ships made it possible to move goods around cheaply enough, the textile sector was one of the first to offshore. A trend you find in most Western countries.
Change in textile and clothing jobs between 1970 and 2000 in several Western countries17.
The final blow came in 2005 (not so long ago!), when the Multi Fibre Arrangement came to an end: this set of rules had capped clothing imports to protect Western countries’ industries. Imports from Asia then soared18, and faced with this competition, what was left of the French textile industry was blown to pieces.
Even TF1 (France’s biggest TV channel) covered it on the evening news in 2005, which tells you something!
And the consequences are more serious than you might think.
3. The consequences of losing the clothing industry
Before we get to the consequences for France, let’s state the obvious: the problem with offshoring is first and foremost a problem for the countries we offshore to.
We politely say that we make things in “low-cost countries”, but you have to look closely at what that means: companies have moved their production to countries where wages are nowhere near enough to live on with dignity. In Bangladesh, for example, even with a 60-hour working week, the minimum monthly wage only reaches 38% of the living wage19, the income needed to cover all basic needs. So in concrete terms, having a t-shirt made there means that the workers, despite enormous hours, won’t be able to house themselves decently, eat their fill or pay for their children’s schooling: it’s a job that lets you survive, but not live. Working conditions there are so disastrous that the population recently rose up, in protests that were violently put down by the government20.
Not to mention that by offshoring production, we also offshored pollution (and even increased it, since environmental standards in these countries are often lower and less enforced than at home). Scandal after scandal has reminded us of this in recent years: rivers polluted by dye works21, endocrine disruptors released into the environment22, excessive lead levels in clothes23, to name just a few.
That is perhaps the main problem with this offshoring: it damages people and the environment in the countries that now do the manufacturing. And since it doesn’t happen at home, we don’t really feel concerned when we buy our clothes. Out of sight, out of mind.
With that said, and even if it’s a little self-centred, let’s talk about the consequences for France.
A- The social problems: not just unemployment
Unlike service companies, which cluster in big cities, factories need space and lower rents. So they tend to create jobs in rural areas and in small and medium-sized towns. Until the 1970s and 80s, France’s regions were covered with factories, each specialised in a different craft: spinning mills in the Nord, hosiery in the Aube, in north-eastern France, weaving in the Vosges…
A 1956 map of France’s textile regions (back when the French still wore hats and dressing gowns, though probably not at the same time).
When the factories closed, the jobs disappeared and never came back: most of the former textile areas (except the region around Lyon and Roanne) still have a higher unemployment rate today than the rest of France24. All the more so because when the factories closed, so did the bakeries, the cafés, the post offices, in short a good part of the local economy shut up shop.
Roubaix, in northern France, once the “city of a thousand chimneys” and former capital of French textiles, now has nearly 30% unemployment25
But unemployment isn’t the only problem: jobs have also become more precarious. Working conditions in textile factories were often hard, but they provided relatively stable jobs (permanent contracts, basically) and sometimes career prospects, not to mention the social benefits that came with certain forms of industrial paternalism26 (education, housing, medical care…). Today, the jobs available in these former industrial areas have changed a lot, with contracts that are often shorter and more precarious27. Industrial jobs have been replaced by service jobs that are less valued, less well paid and often come with precarious working conditions. For example, logistics and transport jobs have risen sharply in the north and east of France28 (to caricature: instead of making things in France, we store and deliver the ones that come from abroad), with low wages, a high share of temp contracts and self-employed workers, unsociable hours for drivers... And as in many rural areas with an ageing population, more and more people work in care and home help, with very difficult working conditions (fragmented hours, very low pay…)29.
And beyond this precariousness, there is also the loss of social status. In the factories, people could build real, valued technical skills30. These jobs gave people genuine pride and a place in local society, all the more so because the clothes and fabrics they made were tangible objects, visible to everyone. And all of this within a rich local life, structured by the presence of the factories: a dense network of bars and cafés, workers’ football clubs, adult-education associations set up by the unions, and so on. Benoît Coquard, a sociologist who carried out a long study31 in eastern France, where many textile factories closed, gives a good illustration: “Industrial activity [...] offered a way to cultivate a shared sense of belonging that people could feel “proud” of. You were from this or that village, there were cafés and bars, associations, a factory just down the road.” Today, jobs in care, home help or logistics, despite their crucial role, carry less social value: they are less visible and no longer give people the same place in the local community. All these difficulties have ended up creating divisions within these areas themselves: people who are out of work or who go from one odd job to the next are heavily stigmatised. Benoît Coquard gives the example of the village football team that goes to an away match and gets called “the losers’ village”.
Beyond the social consequences, there is also the environmental side. We mentioned local pollution above, like discharges into rivers or the spread of endocrine disruptors, but that would be forgetting one form of pollution that knows no borders: greenhouse gases.
B- The environmental problems: let’s not forget CO2
A garment made abroad often emits far more CO2 than one made in France, because the energy that runs the machines in low-cost production countries generally emits far more greenhouse gases than in France and Europe. For example, a garment made in China, where electricity comes mainly from coal-fired power stations, emits twice as much greenhouse gas as the same garment made in France32.
But above all, beyond the pollution per garment, there is the problem of the growing number of garments being made. “Thanks” to offshoring, clothing prices have fallen and clothing consumption in France has more than doubled since the early 1980s33, reaching 40 garments bought per person per year34.
Change in the clothing price index (in the United States): in one generation, the relative price of clothes (compared with other goods) has been divided by three, which explains why we buy so many more of them35.
And producing means polluting: the textile industry’s greenhouse gas emissions have grown at roughly the same pace as production volumes. This increase in the number of garments produced is the main reason the textile industry is failing to cut its greenhouse gas emissions.
OK, fine, textile deindustrialisation was a disaster socially and environmentally, but at least it did our economy some good, right?
We could be content with having offshored an industry that isn’t all that strategic. Unlike food or pharmaceuticals, for example, the textile industry isn’t really essential. If we can no longer feed ourselves, we die. If we can no longer get treatment, we die too. But in a serious crisis, we have more than enough clothes in our wardrobes to survive for years, and we can always mend them36. Admittedly, the mask shortage during the Covid-19 pandemic gave textile factories a semblance of strategic importance. But generally speaking, as this report from the Haut Commissariat au Plan (France’s long-term planning body) points out, fashion products are not vital.
But in fact, while clothes as such aren’t strategic, the trade deficit they generate does end up being strategic.
C- The problems for our economy: the deficit and the risks that come with it
In 2023, we imported so many clothes from abroad that textiles and clothing generated a trade deficit of more than 10 billion euros for France, close to 20% of the country’s overall deficit excluding energy37.
Look back and the picture is even darker, because the textile sector has been in deficit for a very long time: since 1993, France has run up more than 240 billion euros of trade deficit on clothing alone38…
And these repeated trade deficits are not without consequences: to finance them, France has to borrow. And over time, that adds up to a lot of money. In 2023, our net debt to the rest of the world stood at 793 billion euros39: if it keeps growing, it could raise solvency risks for France and trigger a serious financial crisis40 (we are in fact getting close to the 35% of GDP warning threshold set by the EU’s macroeconomic imbalance procedure). And with its 240 billion of accumulated deficits since 1993, clothing bears historical responsibility for nearly a third of that debt. So clothes may not be “vital” or “strategic” products in themselves, but the absence of a clothing industry in France generates a debt that ultimately threatens our economy.
OK, we get it: the disappearance of the textile industry has caused a whole pile of social, environmental and economic damage… But does that mean the solution is to bring it back to France?
After all, the trade balance doesn’t have to be balanced line by line. We could instead choose to reindustrialise other, “higher value-added” sectors and leave textiles, which need more labour on the face of it, to the “low-cost countries”.
Roughly speaking, we could tell ourselves we’ll export Rafale fighter jets and import H&M t-shirts. An adviser to Bruno Le Maire (then France’s finance minister) said as much: “the industrial future isn’t in clothes, it’s in moving upmarket”41 42.
So should we just give up and admit that our textile industry is doomed for good?
4. Should we bring clothing manufacturing back to France?
To answer that question, we need to go back to the basics of industry: machines. We talked above about sewing machines, which need a lot of labour. But that’s only the final stage of making a garment. For the upstream stages, the textile industry uses far more imposing machines. Such as:
A circular knitting machine, for knitting your t-shirts.
A “sanforising” machine, for stabilising fabrics.
A spinning machine for making cotton yarn (it’s Swiss, they really are good at this) (not at football, though).
And year after year, these machines get more and more sophisticated. As a result, in the upstream stages of garment making, labour costs no longer weigh that much compared with the cost of raw materials, machines and the energy to run them.
Today, in theory, the cost gaps between Western countries and low-cost countries are no longer that huge. In a 2018 study43, the federation of textile machinery manufacturers calculated the theoretical cost difference for a fabric between various countries, assuming the factories were equipped with the latest machines. Under those conditions, a metre of fabric made in China would cost only 24% less today than one made in Italy. Because even in Italy, where labour is expensive, it would represent only a small share of the total cost:
Comparison of theoretical manufacturing costs for a fabric (excluding overheads) in 2018: yes, it costs more to manufacture in Italy or Korea, but not that much more…
In the future, with machines improving all the time, energy costs rising and labour costs climbing in some emerging countries, this gap will only shrink.
Seen this way, the textile industry today doesn’t look so different from other sectors like chemicals, cars or aerospace: labour is part of the cost, but not the biggest part. With the best machines everywhere, at every stage of manufacturing, it would be possible to make up for Western countries’ weaker “price competitiveness” with better “non-price competitiveness”: better quality, for example, faster response times, closer geographical proximity or better knowledge of the market. That, by the way, is exactly what Italy has managed to do: it still has a very solid textile industry making fabrics for clothing.
Admittedly, there is still the final sewing stage, which needs a lot of labour (remember, that’s the one with the sewing machines) and can still create big differences in price competitiveness. Sewing shirts or trousers, for example, takes so much time that it’s very hard to reach acceptable costs in France44. But not all garments need that much sewing time: sweaters, socks or even t-shirts, for instance, can be made locally without costs going through the roof. And above all, it is perfectly feasible to send fabrics abroad for the sewing stage, as some brands already do in Portugal, for example (that’s what we do at Loom for our chinos). From an environmental point of view, it makes sense: the machines in the upstream stages are the ones that consume the most energy. Making the fabrics in France or Europe, with lower-carbon energy, reduces the textile industry’s greenhouse gas emissions.
In short, with all due respect to that adviser to Bruno Le Maire, believing that textiles are an industry of the past that should disappear, and that all we need to do is “move upmarket” to build rockets or semiconductors, is a pretty bad idea. In fact, we’ve been told for decades that French industry must specialise in high technology to survive: it has to be said that this strategy hasn’t paid off much. Trying to specialise in “high value-added” industries is probably an illusion if you don’t have the basic skills and no longer have an overall industrial culture. And isn’t it a bit naive to think that emerging countries will be content to make low-end goods? China and India are proving that they can succeed in the very highest technologies (aerospace and electric vehicles in China, for instance, space and semiconductors in India).
In reality, France needs to rebuild an industry for mass-produced goods too (not just luxury products), by investing enough in automation and robotics. That could be in food or cars, but also in textiles: whether in technical fabrics or the upstream stages of garment making, it can be done. This is what can reduce our trade deficit: instead of trying to “move upmarket” and sell things abroad (like planes or handbags), we can also make what we consume locally.
So how do we go about it?
To give the textile sector a second chance, we first need fairer rules of the game. Here’s why.
5. How to give the textile industry a second chance
In the many articles and reports on reindustrialising France, you often read the same things: we need to clear away the “layers of red tape”45, “cut production taxes”46, “steer public procurement”47...
All of that is partly true. But in textiles, we mustn’t forget the elephant in the room: clothing factories in China or Bangladesh produce at very low prices first and foremost because people there are paid poverty wages, because environmental standards are laxer or non-existent, and because the factories run on cheap, ultra-high-carbon energy (Russian gas in China or Bangladesh, for example). All of this skews the country-by-country production cost comparison we showed above: even if French factories run on state-of-the-art machines, the differences in social and environmental standards are such that the cost gap remains too wide.
In short, there is a “reward for bad behaviour”: a competitive advantage for doing things badly.
The polluter’s bonus, illustrated.
If we ever want to see a textile industry reappear in France, we first need to restore the conditions for fair competition with other countries. Ideally, low-cost countries would adopt social and environmental standards as ambitious as ours (or better!), but that is likely to take a long, long time... So in the meantime, we need to penalise, or even ban, imports of clothes made in countries with lower social and environmental standards.
That is also one of the conclusions of the recent report on reindustrialisation that Bruno Le Maire commissioned from industry expert Olivier Lluansi: “Our industry [...] suffers from a major competitiveness deficit. Not through any fault of its own, but because of unfair competition with the other continental powers, North America or Asia. Solving this situation through cost-cutting alone would mean giving up our social model or our environmental ambitions, or both. That is not acceptable. To get back to fair competition while standing by our values, we must reintroduce fair rules into international trade.”
In concrete terms, what would that look like as regulation? It all remains to be invented, but here are a few examples to start with:
Widen the scope of France’s duty-of-vigilance law, which imposes financial penalties on multinationals that violate human and environmental rights. On the basis of this law, NGOs have filed complaints in France against brands that used cotton harvested by Uyghurs in conditions close to slavery. Shouldn’t the law be widened to target brands that produce in factories where the wages paid are too far below the living wage?
Stricter conditions for access to the European market than today. The REACH rules already make it possible to ban imports of clothes containing certain chemicals. But couldn’t these rules be extended to keep the most polluting (or most "exploitative") clothes out of the European market? That is the aim of the future European ESPR regulation on product eco-design, provided it is ambitious enough…
A “bonus-malus” (a reward-and-penalty scheme) based on the gap between the minimum wage and the living wage, a kind of “social border adjustment mechanism”. For example: if a brand produces in a factory where wages are only 30% of the living wage, the brand would pay a penalty to cover the remaining 70%. That penalty would be redistributed to brands producing in factories with better social standards. And it would put an end to brands using blackmail to keep wages low.
An environmental “bonus-malus”, to financially penalise the least responsible clothes and favour the greenest ones, based on the environmental labelling of clothes (which assesses their impact in terms of carbon emissions, toxicity, water pollution and so on). But actually… you know what? This law already exists, and it was even passed unanimously by the National Assembly (the lower house of the French parliament) last March! The problem: to become law, the text had to be voted on by the Senate… and the National Assembly was dissolved in the meantime. So this law is now sinking into oblivion, but with the En Mode Climat movement, we are trying to fight to bring it back.
Results of the National Assembly vote on the law with the environmental bonus-malus for clothes: for once the MPs agreed on something…
Would regulations like these be enough on their own to bring a clothing industry back to life in France? No. They are an absolutely necessary precondition for making our clothing industry more competitive, but sadly they won’t be sufficient.
When a forest has been almost entirely cut down, it doesn’t grow back overnight. To come back to life, the clothing industry will also need well-trained workers, entrepreneurs to set up or take over factories, civil servants who steer public procurement, brands that play the game by buying made in France, land made available by local authorities to build factories, and so on. We will also need a change in our consumer culture: because even with state-of-the-art machines and harmonised social and environmental standards, making a garment in France will cost more than in Bangladesh. So we will have to learn to live with less: accept buying fewer clothes, and mend them more often.
All of this will take years, decades probably. So to get there, as many people as possible need to share the same vision: bringing the manufacturing of the clothes we wear back home is highly desirable, but also entirely possible. France can learn to dress itself again, and it is in its interest to do so. What are we waiting for?
Illustration credit: Matthieu Lemarchal @tamieuh And thank you to everyone who proofread the article: Olivier Lluansi, Anaïs Voy-Gillis, Antoine Camous, Karine Renouil Tiberghien, Flore Berlingen, Pierre Condamine, Maxime Froissant.
Who are we to say this?
You’re reading La Mode à l’Envers, a blog run by the clothing brand Loom. The textile industry is coming apart at the seams, and the planet is footing the bill. So whatever we manage to understand about this industry, we try to explain here. Because making clothes that last is good, but revealing, sharing and inspiring is even more powerful.
By the way, does Loom make clothes in France? Yes, some! At least the ones where we can offer acceptable prices even with French labour costs, in other words: - Those that need proportionally little labour: socks, beanies, scarves, belts, some sweaters, some care products. - Those on which other brands traditionally apply a very large margin, so we can stay competitive with a made-in-France version by cutting ours: sunglasses. - Those whose fabrics are made in France and then sewn in Portugal: chinos, jackets, corduroy overshirts, swim shorts. - Finally, some of our products are made partly with French linen, the only textile fibre we produce locally (along with wool): cotton-linen shirt, band-collar shirt.
The aim, of course, is to offer more and more of them. But to get there, we need the new regulations mentioned in the article above! By the way, we never run ads: if you like what we write and want more, subscribe to our newsletter by clicking here. Promise: we’ll write to you once a month, tops.
Notes
1 : Source: FIMIF (a French made-in-France consumer association). Estimate confirmed by this DEFI IFM study in 2024. 2 : Whereas in the 1960s, almost all our clothes were still made in France (customs statistics show very few clothing imports at the time). 3 : Ouest France 2020 4 : Les Echos 2024 5 : Fashion Network 2024 6 : Figures from URSSAF (the French social security contributions agency) for textile APE codes (source). You sometimes also read the figure of 60,000 jobs for the textile and clothing industry in France (excluding leather). That isn’t quite what we get here with the URSSAF figures (36,000 + 31,000 = 67,000 jobs). That figure comes from a calculation by OPCO (the industry’s training body), whose scope isn’t exactly the same: it cross-references all APE codes with identifiers from the textile collective agreements. It is therefore more precise, but it doesn’t provide the textile / garment-making breakdown we needed here to make our point. 7 : Source: URSSAF 8 : 64% of leather goods made in France are handbags (source: INSEE). 9 : Le Monde 2019 10 : Further down we mention the 50 factories working on everyday clothing. If we assume 200 people per factory, which is already very optimistic, that makes 10,000 employees. 11 : 8,000 factories according to this report. 12 : Sources: Fashion Network and La Voix du Nord. 13 : INSEE report on Made in France. 14 : Source: Textiles and clothing: facing the challenges (“Textile et vêtement : faire face aux mutations”), OECD report, 2005. 15 : Why Robots Can’t Sew Your T-Shirt, Harris Quinn for Wired 16 : What is SMV in garments industry, Textile Scholars. 17 : Textiles and clothing: facing the challenges, OECD report, 2005. 18 : EU: clothing imports from China up 15% in January-February, Fashion Network (23/05/2006) 19 : Source: The Industry We Want 20 : Source: France 24 21 : Asian rivers are turning black. And our colorful closets are to blame, CNN 2020. 22 : Toxic Threads: the big fashion stitch-up (in French), Greenpeace 2012. 23 : Martin Weill’s documentary “Victimes de la Mode” (Fashion Victims), TMC 2022: lead levels measured at 4 times the REACH limit in a Shein garment imported into France. 24 : Unemployment rate, third quarter of 2021 according to INSEE: 10.0% in the Nord, 10.2% in the Aube, 8.5% in the Vosges vs. 7.9% in mainland France. 25 : Source: INSEE 2020: 29.7% unemployment among 15-64 year-olds in Roubaix. And with the collapse of Camaïeu, which had its head office in Roubaix, misfortune keeps piling up on a city that is, more than ever, a victim of low-cost textiles. 26 : For example at Boussac textile: schools were set up, nurseries opened near the factories, housing built, along with domestic-science schools and apprenticeship schools. 27 : “In 2017, the share of employees on a permanent contract was 44% in industry versus 28% in services. The industrial sector thus gives the middle class jobs that are both better paid and more stable” Source: (Accelerated) deindustrialisation: the role of macroeconomic policies (in French), François Geerolf and Thomas Grjebine. 28 : DARES journal Travail et Emploi, 2020 (DARES is the French labour ministry’s statistics department): “Given the labour requirements involved, areas [...] in industrial decline are targeted as a priority, so that logistics becomes a favoured development strategy for revitalising so-called distressed areas. In northern France, in the east along the border, in the greater Paris area and in the Rhône basin, working-class employment areas with a strong logistics component have thus taken shape. 29 : “Doing home care” in the countryside: professional identities of home helpers for the elderly in rural areas (in French), 2023. 30 : Textile professionals: building a proud self-awareness (in French), Françoise Faye, 2005. 31 : Benoît Coquard, Ceux qui restent (Those who stay: making a life in declining rural areas) (La Découverte, 2019). 32 : Assessment of Carbon Footprint for the Textile Sector in France, Cycleco, February 2021: 20.90 kg CO2eq per kilo of textile made entirely in France vs 43.43 kg in China. 33 : In 1984, clothing consumption in France was 1.3 billion items, so 23 garments per inhabitant. Source: 1984 INSEE survey of 7,500 households. Today it stands at 2.7 billion garments according to Refashion, the industry’s recycling body. 34 : Source: Refashion 2022 activity report. 3.3 billion * 83% clothing / 67.8 million inhabitants * 99% = 40 garments per inhabitant. Add shoes and household linen and you get almost 50 textile items per French person. 35 : Source: FRED Economic Data. 36 : Governments in countries at war actively encouraged clothing repair, by the way: see the Make Do and Mend campaign in the United Kingdom during the Second World War 37 : Cumulative textile + clothing deficit since 1993 according to French customs (excluding leather) (source). 38 : Source: French customs, calculations in this document. 39 : Our trade deficits help widen our current account deficits (which also take into account trade in services, among other things). Over time, this generates external debt, technically known as France’s “net international investment position”. The fact that it is negative means that foreigners hold more assets in France than French residents hold abroad. More information on the Banque de France website. 40 : “The international investment position makes it possible to assess a country’s risk of experiencing a financial crisis in the short term (a sudden drying-up of liquidity) or the long term (risk of insolvency), in line with the analytical methods generally used by international organisations". Source: The international investment position: measurement and usefulness for monetary policy and financial stability (in French), Banque de France, 2003. 41 : Marine Le Pen and Eric Zemmour sketch out their economic proposals at the Made in France trade show (in French), Ivanne Trippenbach for Le Monde (15/11/2021). 42 : This belief in moving upmarket is in line with the position of the 2012 Gallois report, “Pact for the competitiveness of French industry”, whose second part is titled “An industrial ambition: moving upmarket”. 43 : Source: IPCC 2018 44 : To give you an idea: a shirt takes around 30 minutes of sewing time, so with an hourly labour cost of almost 40 euros in France, that would come to €20 of production cost for French labour alone. Apply a classic brand multiple (x5) and that makes €100 just for this stage.45 : Reindustrialisation: why France has everything it takes to succeed (in French), Augustin de Romanet for Le Cercle des Economistes (27/11/2023) 46 : Bruno Le Maire: “Cutting production taxes is one of the conditions for reindustrialising France” (in French), L’Opinion (07/10/2022) 47 : Reindustrialising France by 2035 looks more like guerrilla warfare than a “Blitzkrieg” (in French), Solène Davesne for L’Usine Nouvelle (08/06/2024)
This article was originally written in French, our native language. Apologies in advance if anything reads a little awkwardly – you can write to us at hello@loom.fr to help us improve our translations.
Our mission is to change the fashion industry – including the way it is funded. To let Loom stay an ethical company, it was hundreds of individuals – not investment funds – who invested in us. And it all started with this article, published in March 2019.
You can’t change an industry without asking one fundamental question: where does the money come from?
When you start a company, there are two possible strategies:
1/ The startup strategy, in other words exponential growth with the ambition of conquering the world as fast as possible 2/ The SME strategy, which means building a company that grows slowly but surely
Neither vision is better than the other: the two models simply reflect two different mindsets.
But these days, it feels like nobody starting a company even asks themselves the question: they want to create a startup. Because the media talk about nothing else, because it sounds cooler at parties (well, at some parties) and because, potentially, it could make them very rich.
These startups usually go on to “raise funds”, in other words ask for money from investment funds (= organisations that place large sums of private money in order to earn the biggest possible return). To pay that money back, these funds have to recover what they invested in the startups – with as much return as possible – within 4 to 10 years. There are three ways to do that:
1/ By selling the startup to another company. 2/ By selling the startup to another investment fund. 3/ By taking it public on the stock market (rarer).
Under no circumstances can the startup stay an independent company (except perhaps in the extremely rare case where it takes on debt to buy back its own independence). Once it has raised funds, it has to grow as fast as possible in order to be sold for as much as possible. That’s the growth race. Of course, some funds are more patient than others and stand by founders even through the hard times, but the long-term goal stays the same: sell as soon as possible, for the biggest possible gain.
Investment funds’ favourite image: the racing car (when it isn’t a rocket).
For some types of company, this rapid growth is essential, especially when they need to reach “critical mass” very quickly: Airbnb, for instance, needs lots of listings for tourists and lots of tourists for flat owners.
The real problem is that today, far too many new companies see themselves as startups. They raise funds and then throw themselves into a growth race that brings them far more risk than reward.
Do things too fast and you do them less well
Faster, but neither stronger nor better.
In a study of more than 3,000 startups, Stanford academics showed that the number one cause of failure was precisely premature growth.
Imagine you have just raised several million euros. If your company doesn’t grow fast enough, you’re trapped. You’ll spend on advertising instead of improving your product, hire a sales team instead of an engineering team, and so on.
Remember Groupon? One year after it was founded, the company was valued at 1 billion dollars. Today it’s a shadow of its former self. Why? Because instead of paying merchants properly, it blew everything on advertising and international expansion.
Fast growth undermines your chances of building lasting growth.
Like a tree that never had time to grow solid roots, growing too fast creates cracks that leave the company at the mercy of the first storm. For the investors, it’s no big deal: their money is spread across dozens of startups, so one that “works” is enough to make up for 15 that fail... For the people who lose their jobs when the company shuts its doors, it’s a bit more of a problem.
But this fragility is the least of it. The rapid growth of startups raises three other, far more worrying problems.
The collateral damage of rapid growth
There you go. It was bound to happen sooner or later.
Consumers foot the bill
There’s a very fashionable term in Silicon Valley: blitzscaling (“lightning growth”). It means growing as fast as possible to crush the competition – without necessarily building the best service or the best product.
Think of car/bike/scooter sharing, or on-demand delivery. Does Uber getting even bigger change anything for its customers? No. Waiting times are already so short that recruiting more drivers won’t noticeably reduce them. On the other hand, the bigger Uber gets, the better its chances of wiping out the competition... so the company pours ever more money into marketing and advertising.
Deliveroo and Uber Eats saw off Take Eat Easy and Foodora with wave after wave of ads on Facebook and in the metro. And once one of those two startups has a monopoly, it may well recoup its money through meal prices, courier pay and restaurant commissions.
In short: it’s cheap today, but tomorrow we’ll probably pay dearly for it.
Stress and pressure on the staff
With this growth race, the pace of work in a startup can become absurd. Special mention to Nikolay Storonsky, founder of the online bank Revolut, who asks his teams to work 12 to 13 hours a day and who declared: “I don’t understand how having a personal life can help you build a startup” (sic). It’s obviously not like that in every startup, but if the founders aren’t careful, the hours can quickly wreck their employees’ work-life balance.
A hefty bill for society
These startups, pumped full of investment-fund money, are upending our jobs and our habits at unprecedented speed. So fast that society has no time to adjust. Yes, Uber created hundreds of thousands of driving jobs in a few years… but it will destroy them even faster once it rolls out self-driving cars. How will governments protect people who find themselves unemployed overnight? (And that’s without mentioning how precarious all these new jobs are, whether it’s driving cars, delivering meals or recharging scooter batteries.) Startups are often born with the aim of making the world a better place, but the way they are funded can sometimes lead to the opposite.
And the planet picks up the pieces
Above all, these companies grow so fast that they have no time to measure their impact on the environment (assuming they care). They think in years, while environmental consequences are measured in decades or centuries. One example: by churning out millions of junk bikes that end up piled high in landfills, bike-sharing startups aren’t giving much thought to the world’s dwindling metal reserves.
Nature doesn’t run on an investment fund’s timescale.
Yvon Chouinard, founder of Patagonia (in 1969, as that glorious moustache testifies).
However admirable the founders’ original values, the growth race makes them irrelevant.
Without ethical finance, there can be no ethical company.
Patagonia is often held up as the ultimate example of an ethical company: deeply committed to protecting the environment, and a business success with more than 2,000 employees today. But would the brand still exist if it had been forced to keep up breakneck growth, even at the expense of quality? Probably not. When it decided in 1991 to cap its annual growth at 5%, which investment fund would have accepted that decision?
Patagonia belongs to nobody but its founders. That is what guarantees its freedom to act (and lets it threaten to take Trump to court).
Because in the textile industry, the growth race is especially dangerous:
It destroys the planet.
It hurts people.
It drags down the quality of clothes.
It pushes people to overconsume.
Will Loom ever reach Patagonia’s level of commitment? We’re working flat out on it, but nothing is certain. What we do know is that if we raise funds the conventional way, we will never get there.
We want to be free to leave a product out of stock for months if we think our prototypes aren’t good enough.
We want to be free to close our site on Black Friday to call out the absurdity of these promotions.
We want to be free to switch to organic cotton and cut our margin if that’s the price to pay.
We want to be free to have a rant and show what goes on behind the scenes, without worrying about frightening off a potential buyer.
Rant, example #6.
And yet, we want to grow
Even so, we are convinced that we need to grow if we want to really drive change.
First, to keep up with demand: right now, our products sell out barely a few weeks after going on sale. For some brands that might be a strategy; for us, it can only ever be temporary.
Yes, we know...
Second, getting bigger is our chance to turn the fashion industry the right way round. The bigger we are, the further our voice will carry, on the consumer side as much as on the manufacturing side. We dream of a day when clothes that last are the norm rather than the exception. We would like producing in Bangladesh to become unthinkable. We want environmental awareness to be at the heart of the textile industry, rather than boiling down to a CSR job created right after an environmental scandal.
In short, we have to grow. Grow at our own pace, without compromising on quality or ethics; grow knowing that our growth isn’t meant to be infinite, just enough to reach a sufficient size. And to grow, Loom needs money.
“But why do you need money if more and more people are buying from you?” Excellent question, Dominique.
To have products in stock, we order them and pay whoever makes them before we can sell them. That gap – our “working capital requirement” – is why we need money. The bigger we get, the bigger that requirement gets (up to a certain point).
Become a Loom shareholder
We would love to see our community own a share of our company. From the very beginning, you have helped create our clothes, improve them and spread the word about the brand. The logical next step1 is to give you the chance to become Loom shareholders.
“But if I invest in your company, what do I get in return (apart from a clear conscience)?” Honestly, Dominique, it’s one good question after another with you.
It’s very simple: we will pay you dividends. No, it isn’t a dirty word, and no, it isn’t just for fat men smoking cigars.
Classic photo of shareholders collecting dividends in a normal company.
Once we make enough profit, we will pay part of it back to you2. Little by little, year after year, you will get your initial investment back and (we hope) more. We won’t lie to you: we will do our best, but we might fail, or it might take a long time. So only invest what you are prepared to lose.
Classic photo of shareholders collecting dividends at Loom.
If you follow Loom, it’s because you too think the world of textiles has a problem. Being part of the solution means changing the way we dress. But also the way our companies work.
Update, April 2019
We were told that small shareholders would be nothing but trouble. That crowdfunding was a bad idea. That we wouldn’t raise enough money. That big investors are awfully convenient, all things considered. For the reasons explained above, we asked you to invest in Loom anyway.
It took just 3 days to raise 700,000 euros. More than 600 people answered the call. The team at LITA.co can’t believe it. Our campaign was supposed to run until the end of April. In the end, it was wrapped up on 31 March, at midnight.
You have given us the freedom we needed to keep going. We will never have to enter an absurd growth race. Nobody will ask us to sell Loom for the highest possible price. And we won’t keep quiet about our convictions for fear of scaring off a potential investor. In short, we won. And we received so many messages of support that we understood something: small shareholders aren’t trouble, they’re an enormous strength.
Thanks to your support, Loom can carry on the fight. Thanks to those of you who invested. But also to those of you who buy our clothes, answer our surveys and tell us how to improve. Those of you who tell your friends about us, who read our newsletters, who share our articles. In short, thanks to every one of you who, in one way or another, is part of this project. Today, Loom is no longer just our brand. It’s yours too.
Julia Faure and Guillaume Declair, co-founders of Loom
Footnotes
1 We have also activated three other sources of funding. 1/ Bank loans: we go through an ethical bank, la Nef, which focuses on projects with a social or environmental purpose (other banks run a mile when we tell them we sell online). 2/ So-called “evergreen” funds, which don’t have to give the money back to their own investors and therefore won’t force rapid growth on us. They are starting to appear, but – for now – they invest in companies much bigger than ours. 3/ “Business angels”: people who have often started a company themselves in the past and invest in other companies. Some have already agreed to invest in Loom.
2 Each year, we will have three options for what to do with the profits: reinvest them in Loom, share them with employees through profit-sharing schemes, or pay them out to shareholders as dividends in proportion to the number of shares they hold.
Who are we to say this?
You’re reading La Mode à l’Envers, a blog run by the clothing brand Loom. The textile industry is in a sorry state, and the planet is footing the bill. So whatever we manage to understand about this industry, we try to explain here. Because making clothes that last is good, but revealing, sharing and inspiring is even more powerful.
If you like what we write and want more, subscribe to our newsletter by clicking here. We promise: we write rarely and we never spam.
Of course, founders can block a sale for a few years… But in practice it’s fairly rare, and there is no guarantee the funds will go along with it. A liquidity clause – written into almost every investment agreement – in theory lets the fund trigger a sale on its own.
Usually after several successive funding rounds (Criteo in 2013 or Showroomprivé in 2015, for example).
Some will tell you that a startup can buy back the fund’s shares with a bank loan. It’s true that it has happened (Wistia and Buffer, for example), but in practice it’s quite complicated.
So far we have managed to get around this problem with pre-orders, but in the medium term we would like to stop doing them.
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.